
Table of Contents
Frequently Asked Questions
Does business interruption insurance cover a closure ordered by the government?
Usually not. Standard wording requires insured physical damage to the premises before the policy pays, so a closure order without damage is normally declined. Some policies add limited extensions for specific events, so read the infectious disease and public authority wording before you buy.
Is business interruption insurance compulsory for companies in the UAE?
No general law requires every company to hold it. Landlords, lenders or client contracts may require proof of cover as a condition of a lease, finance or contract. Mandatory lines such as medical insurance are separate and do not include income protection.
How is the sum insured calculated for lost income cover?
The sum insured is usually based on annual gross profit plus insured standing charges, such as rent and salaries that continue during the loss. Use current accounts and realistic forecasts rather than last year's peak or low. If the declared figure is too low, the insurer can reduce the payout proportionally.
How long should an indemnity period be for a small trading company?
Set it to match how long the business needs to rebuild and return to its pre-loss trading position. Include lead times for fit-out, imported stock or equipment and any approvals. A period that is too short ends before trading recovers, leaving you to cover the gap.
Can a home-based or flexi-desk company claim for interruption losses?
Only if insured physical damage disrupts its operations. Flexi-desk and virtual setups carry little physical exposure, so the sum insured is often small and professional liability may matter more. A company holding stock or equipment at a third-party site should check whose policy covers stock and lost income.
What documents does an insurer ask for after a loss?
Expect requests for management accounts, VAT returns, payroll records, invoices and fixed cost schedules, plus photographs and incident reports. The loss adjuster uses these to verify the cause and calculate the payout. Clean bookkeeping speeds up settlement, and a Meydan Free Zone company can use mAccounting for bookkeeping, VAT registration support and Corporate Tax support.
Does the policy pay if a key supplier suffers a fire?
Only if the policy includes a supplier or customer premises extension. Without it, damage at a third party's site falls outside standard cover. Businesses that rely on a single supplier should ask insurers to price this extension.
Topic Summary
What Business Interruption Insurance in the UAE Covers
Business interruption insurance in the UAE compensates a company for lost income and ongoing costs after an insured event, such as fire or flood, damages its premises. It is normally an extension to a property policy and pays only when physical damage triggers the claim.
How Business Interruption Cover Is Regulated in the UAE
Insurance in the UAE is regulated at federal level by the Central Bank of the UAE, which licenses insurers and oversees policy conduct. You buy business interruption cover from a licensed insurer or broker, not from a free zone authority, which does not issue or regulate insurance products.
How Cover Limits and Indemnity Periods Work
A business interruption policy pays up to a sum insured, usually based on annual gross profit, for a set indemnity period. The indemnity period is how long the insurer pays after the damage. It should match the time your business needs to rebuild and regain its pre-loss trading position.
Common Exclusions That Reduce Claims
Business interruption policies exclude losses not caused by insured physical damage, along with war, certain pandemic-related closures, wear and tear, and deliberate acts. Many policies also limit utilities failure and supplier loss unless a named extension is added and priced.
How to Make a Business Interruption Claim in the UAE
To make a business interruption claim, notify the insurer promptly, secure the premises, document the damage and submit financial records showing lost profit. The insurer appoints a loss adjuster, who verifies the cause and calculates the payout against your sum insured and indemnity period.
Business Interruption Insurance vs Related Policies
Business interruption insurance covers lost income after physical damage, while property insurance repairs assets and liability insurance covers third-party claims. Each answers a different loss, so most founders need property cover with an interruption extension plus liability cover.
What Business Interruption Insurance Means for a Meydan Free Zone Company
A Meydan Free Zone company buys business interruption cover from a licensed insurer, based on its premises, activity and income. Meydan Free Zone issues the Business License digitally. mAccounting offers bookkeeping, VAT registration support and Corporate Tax support, which help produce the figures behind a claim.
Business Interruption Insurance in the UAE
Many founders insure their stock, fit-out and equipment, then assume the same policy replaces lost income if a fire or flood shuts the doors. Usually it doesn't, because business interruption insurance pays only after insured physical damage, and that condition catches people out at claim stage. This guide explains what the cover pays for, how limits and indemnity periods are set, and how to compare policies before you buy.
What Business Interruption Insurance in the UAE Covers
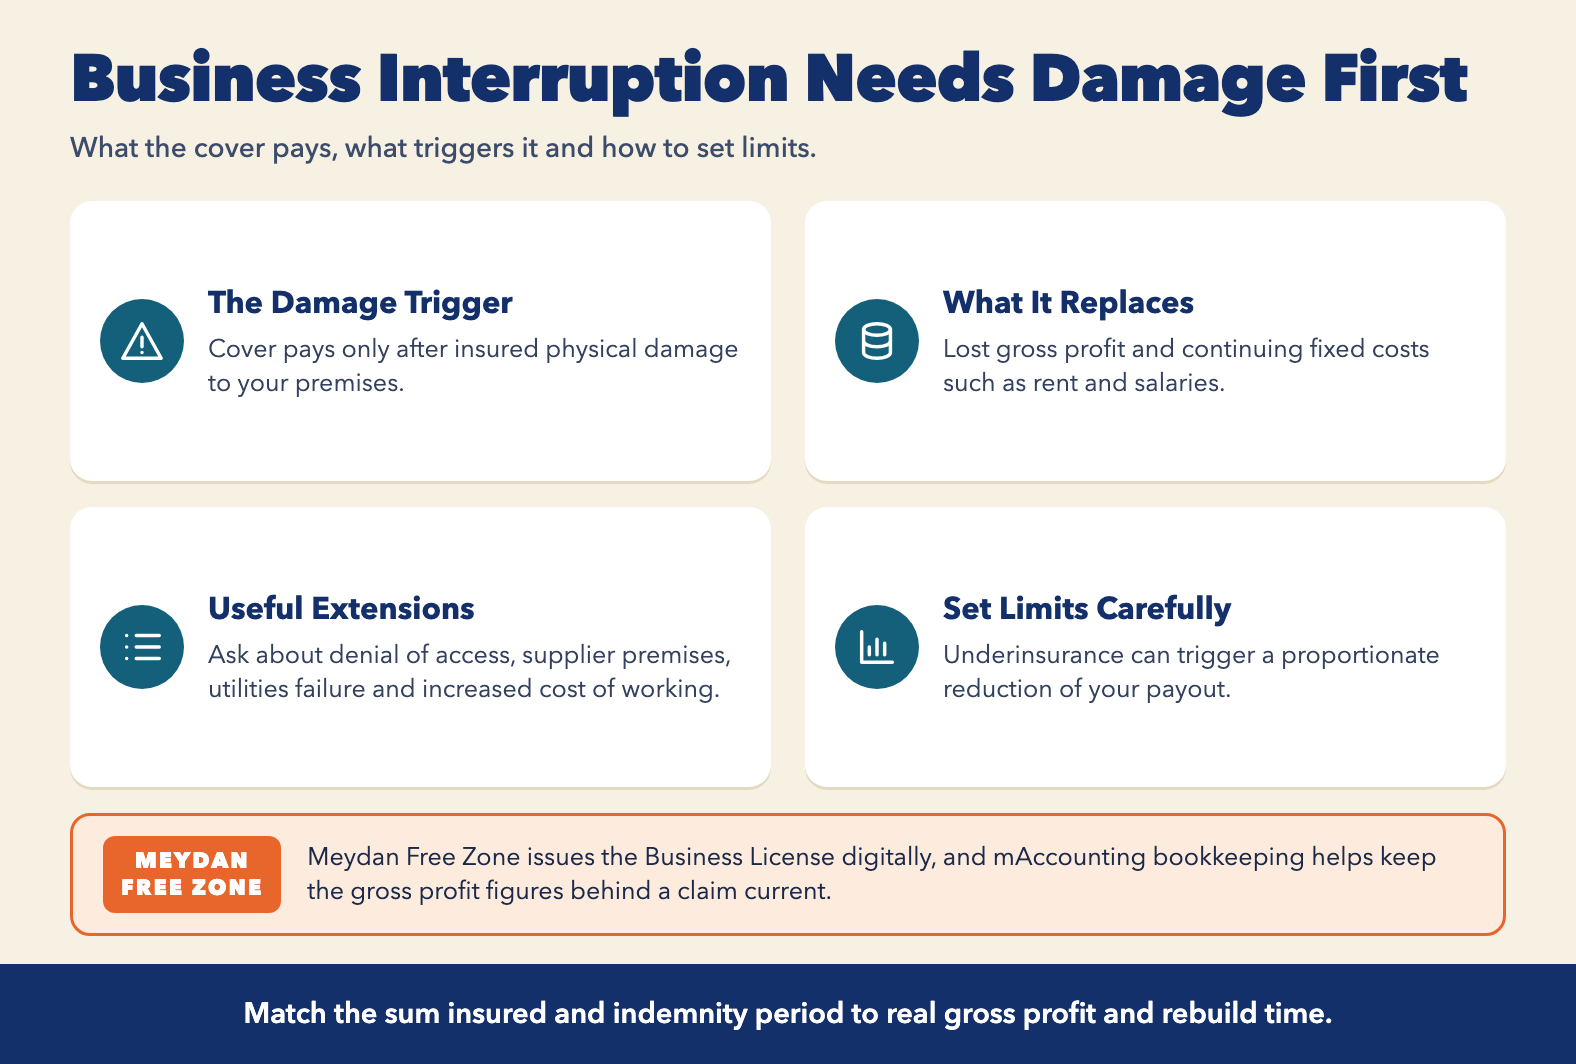
Business interruption insurance in the UAE compensates a company for lost income and ongoing costs after an insured event, such as fire or flood, damages its premises. It is normally an extension to a property policy and pays only when physical damage triggers the claim.
Definition and Core Purpose
The cover replaces lost gross profit while operations are suspended. It also pays fixed costs that continue, such as rent, salaries and loan repayments. Say a Dubai café closes for eight weeks after a kitchen fire. Property cover repairs the kitchen. The interruption extension covers lost profit and staff wages over those eight weeks. For fire exposure specifically, see the guide on how to setup fire insurance business in Dubai.
The Physical Damage Trigger
Insured damage to the premises must come first. Market downturns and lost customers are not covered. A trader whose sales fall because a neighbouring building closes the access road has no claim without a denial of access extension.
Common Extensions Worth Asking About
- Denial of access to your premises.
- Supplier and customer premises.
- Utilities failure.
- Increased cost of working.
An e-commerce seller relying on one overseas supplier needs the supplier extension. Without it, a shutdown there leaves the seller uncovered.
How Business Interruption Cover Is Regulated in the UAE
Insurance in the UAE is regulated at federal level by the Central Bank of the UAE, which licenses insurers and oversees policy conduct. You buy business interruption cover from a licensed insurer or broker, not from a free zone authority, which does not issue or regulate insurance products.
Who Supervises Insurers
If you receive a quote from an unfamiliar provider, confirm its licensed status on the regulator's registers before paying a premium. Brokers and intermediaries are supervised too. If you want advice from a specialist, see how an insurance consultancies business operates.
Mandatory and Optional Cover
Interruption cover is not a general legal requirement for companies. Landlords, lenders or contracts may demand it, though. A lender might require proof before releasing equipment finance. Mandatory lines, such as health insurance for employees, are separate.
How Cover Limits and Indemnity Periods Work
A business interruption policy pays up to a sum insured, usually based on annual gross profit, for a set indemnity period. The indemnity period is how long the insurer pays after the damage. It should match the time your business needs to rebuild and regain its pre-loss trading position.
Setting the Sum Insured
The figure rests on gross profit plus insured standing charges. Use current accounts and forecasts, not last year's peak or trough. Underinsurance can trigger a proportionate reduction. A consultancy that declares gross profit far below its real run rate will see the payout cut in the same proportion.
Choosing an Indemnity Period
Consider lead times for fit-out, imported equipment and licensing approvals. A clinic waiting for imported equipment may need an 18-month period rather than six months. Short periods run out before trading recovers.
Waiting Periods and Deductibles
- A time excess leaves the first days of a loss unpaid.
- A 72-hour waiting period means a three-day outage pays nothing.
- Check how the policy defines the start of the period.
- Compare deductibles against your cash reserves.
Common Exclusions That Reduce Claims
Business interruption policies exclude losses not caused by insured physical damage, along with war, certain pandemic-related closures, wear and tear, and deliberate acts. Many policies also limit utilities failure and supplier loss unless a named extension is added and priced.
Standard Policy Exclusions
- War and related perils.
- Gradual deterioration and poor maintenance.
- Government-ordered closures without physical damage.
- Infectious disease, so read this wording closely.
A restaurant closed by a health order, with no physical damage, will find its business interruption claim declined.
Conditions That Void a Claim
Late notification, inaccurate declarations at renewal and missing financial records all weaken a claim. A company that can't produce monthly management accounts invites the insurer to dispute the loss figure. Liability exposures sit in separate policies, covered in general liability vs professional liability.
How to Make a Business Interruption Claim in the UAE
To make a business interruption claim, notify the insurer promptly, secure the premises, document the damage and submit financial records showing lost profit. The insurer appoints a loss adjuster, who verifies the cause and calculates the payout against your sum insured and indemnity period.
Numbered Claim Process
- Notify the insurer or broker as soon as the loss occurs.
- Limit further damage and keep photographs as evidence.
- Report the incident where required, such as to police or civil defence for fire.
- Submit management accounts, VAT returns, payroll and invoices.
- Cooperate with the loss adjuster's assessment.
After a warehouse flood, a trader who notifies the insurer the same day and supplies twelve months of accounts gives the adjuster what's needed immediately.
Records That Support the Figures
Bookkeeping that ties to VAT and Corporate Tax filings with the Federal Tax Authority strengthens a claim. Keep payroll and fixed-cost schedules current, and separate business from personal spending. A company with clean ledgers usually settles faster, while one with gaps faces repeated information requests.
Business Interruption Insurance vs Related Policies
Business interruption insurance covers lost income after physical damage, while property insurance repairs assets and liability insurance covers third-party claims. Each answers a different loss, so most founders need property cover with an interruption extension plus liability cover.
Side-by-Side Comparison
| Feature | Business Interruption Insurance | Property or Liability Insurance |
|---|---|---|
| What it pays for | Lost gross profit and continuing fixed costs | Property: repair or replacement of assets. Liability: third-party claims |
| Trigger event | Insured physical damage that suspends trading | Damage to assets, or injury or loss caused to a third party |
| Typical basis for the sum insured | Annual gross profit plus standing charges | Asset replacement value, or a chosen liability limit |
| Main exclusions | Market downturn, closures without damage, war | Wear and tear, deliberate acts, contractual liabilities |
| Who it suits | Businesses reliant on premises, stock or equipment | Every operating business, weighted by activity |
Which Gap Matters Most for Your Model
Asset-heavy businesses prioritise property and interruption. Service firms prioritise professional liability. A design studio might hold professional liability for client disputes and a fire policy with interruption cover for its office. A solo consultant on a flexi-desk may weigh professional liability above a large interruption sum. Digital firms should also weigh cyber and equipment cover.
What Business Interruption Insurance Means for a Meydan Free Zone Company
A Meydan Free Zone company buys business interruption cover from a licensed insurer, based on its premises, activity and income. Meydan Free Zone issues the Business License digitally. mAccounting offers bookkeeping, VAT registration support and Corporate Tax support, which help produce the figures behind a claim.
Matching Cover to Your Premises and Activity
Flexi-desk and virtual setups carry little physical exposure. Trading and stock-holding firms carry more. A company storing goods at a third-party warehouse should check whose policy covers stock and lost income, and what the landlord's policy leaves to you.
Keeping Records Claim-Ready
Accurate gross profit figures set a defensible sum insured. A founder using monthly bookkeeping can update the declared figure at each renewal. Digital records also speed up loss adjustment.
Costs to Plan For
Premiums are a recurring cost, reviewed at renewal. They depend on activity, location and sum insured, and any quote is an estimate until the insurer confirms it. Insurance sits outside your license and visa costs, so add expected premiums to the setup figures from the Cost Calculator.
Free Business Setup Cost Calculator
Calculate NowConclusion
Business interruption insurance in the UAE protects income only after insured physical damage. It works when the sum insured, indemnity period and financial records are right. Set limits from real accounts, choose extensions for your actual dependencies and confirm the insurer is licensed.
With Meydan Free Zone, mAccounting bookkeeping can keep your gross profit figures current. That leaves one decision: which insurer's wording fits your premises and activity.
Ready to Launch Your Business in Dubai?
Let's Connect