Table of Contents
Frequently Asked Questions
Is Contractors All Risk insurance mandatory for construction projects in the UAE?
Whether CAR cover is mandatory depends on the project. Main contracts, developers and lenders commonly require it before site access, so it becomes a binding condition of the contract. Check the insurance clause in your contract and the requirements of the relevant emirate authority for the site.
What does a Contractors All Risk policy not cover on a construction site?
Standard exclusions include wear and tear, the cost of correcting faulty workmanship, war and nuclear risks, and delay or loss of profit unless added. Existing structures and the contractor's own plant and machinery often need separate cover. Read the exclusions against the contract's insurance clause before signing.
Who should buy the policy, the contractor or the project owner?
The main contractor usually arranges the policy, with the owner named as co-insured and any lender noted as an interested party. The contract can instead make the owner responsible. The insurance clause decides who buys the policy, who pays the premium and who bears the deductible.
Can a subcontractor be covered under the main contractor's policy?
Yes. Subcontractors are often named as co-insured under the main policy, and their share of the premium is usually recovered through the subcontract price. If the main policy does not extend to them, they must carry their own cover. The subcontract terms set out which route applies.
How long does cover last after a project is completed?
Standard cover runs from site start to handover. An optional maintenance period extension can continue cover through the defects liability phase, for example if the contract requires 12 months. Notify the insurer of any programme extension to avoid a gap in cover.
What affects the premium for a construction project policy?
Insurers price each project individually. They review contract value, project type, location, construction period, site conditions, subcontracting level, contractor experience, deductible and claims history. Quotations are estimates until underwriting is complete, and a higher deductible lowers the premium but increases the risk you retain.
Is VAT charged on construction insurance premiums in the UAE?
Premiums are quoted in AED and are generally subject to VAT under Federal Tax Authority rules. Some insurance services may be treated differently, so confirm the treatment on your quotation. A Meydan Free Zone company can use mAccounting for bookkeeping and VAT registration support.
How is CAR cover different from general liability insurance?
CAR is project-specific and covers physical loss to the works, materials and site equipment, plus third-party liability arising from the works. General liability covers ongoing business operations. Neither covers design errors, which need professional indemnity, so contractors often hold several policies together.
Topic Summary
What Contractors All Risk Insurance in the UAE Covers
Contractors all risk insurance in the UAE is a policy that covers physical loss or damage to construction works, materials and site equipment during a project, plus third-party liability for injury or property damage caused by the works. It runs from site start to handover, with an optional maintenance period afterwards.
Who Regulates Construction Insurance in the UAE
Insurance companies in the UAE are regulated at federal level by the Central Bank of the UAE, which took over insurance supervision from the former Insurance Authority. You buy CAR cover from a licensed insurer, directly or through a licensed broker. Clients, lenders and the contract add their own requirements.
Who Needs a Policy and Who Pays for It
CAR cover is normally arranged by the main contractor, though the contract can make the project owner responsible. Subcontractors are usually named as co-insured or must carry their own cover. The insurance clause decides who buys the policy, who pays the premium and who holds the deductible.
What Drives the Premium and Policy Terms
The CAR premium depends on contract value, project type, location, construction period, contractor experience, deductible level and claims history. Insurers price each project individually, so quotations are estimates until underwriting is complete. Premiums are quoted in AED and are generally subject to VAT.
How to Arrange Cover
To arrange CAR cover, confirm the contract's insurance clause, gather project details, request quotations through a licensed insurer or broker, compare terms and exclusions, issue the policy before site start, and give the certificate to the client. Review cover after any change in scope or programme.
CAR Insurance Compared With Other Business Policies
Contractors all risk insurance protects the project and third parties during construction, while general liability, professional indemnity and workmen's compensation cover separate exposures. You typically need several policies together, because CAR does not replace employee, design or ongoing business cover.
What CAR Cover Means for a Meydan Free Zone Company
For a Meydan Free Zone company, the first step is to confirm the licensed activity matches your site work, then budget CAR cover as a recurring project cost. Meydan Free Zone issues the Business License digitally after registration, and mAccounting offers bookkeeping and VAT registration support.
Contractors All Risk Insurance in the UAE
Many founders entering UAE construction assume the main contract and a general liability policy will cover site losses. They usually won't, and a fire, flood or crane collapse on a live site can land on the contractor's balance sheet.
This guide explains what Contractors All Risk (CAR) cover includes, who regulates it, who buys it and what drives the premium. It also shows how to arrange cover before the client asks for the certificate.
What Contractors All Risk Insurance in the UAE Covers
Contractors all risk insurance in the UAE is a policy that covers physical loss or damage to construction works, materials and site equipment during a project, plus third-party liability for injury or property damage caused by the works. It runs from site start to handover, with an optional maintenance period afterwards.
Section I: Material Damage to the Works
This section covers permanent works, temporary works and materials on site against sudden, unforeseen physical loss. Typical perils include fire, flood, theft and collapse, subject to the policy wording. The sum insured is normally the full contract value, including materials the client supplies.
Say a fit-out contractor's stored materials are damaged by a water leak before handover. The policy responds to the reinstatement cost.
Section II: Third-Party Liability
This section covers your legal liability for injury to third parties or damage to neighbouring property arising from site work. It carries a separate limit of indemnity, stated per occurrence. If excavation damages an adjacent building's boundary wall, this section answers the claim. It differs from ongoing business cover, as general liability vs. professional liability explains.
Common Exclusions to Check Before Signing
- Wear and tear, and the cost of faulty workmanship.
- War and nuclear risks.
- Delay and loss of profit, unless added.
- Existing structures and owned plant, unless declared.
One contractor assumed its excavator was covered. The policy excluded owned machinery that wasn't declared. Read every exclusion against the contract's insurance clause.
Who Regulates Construction Insurance in the UAE
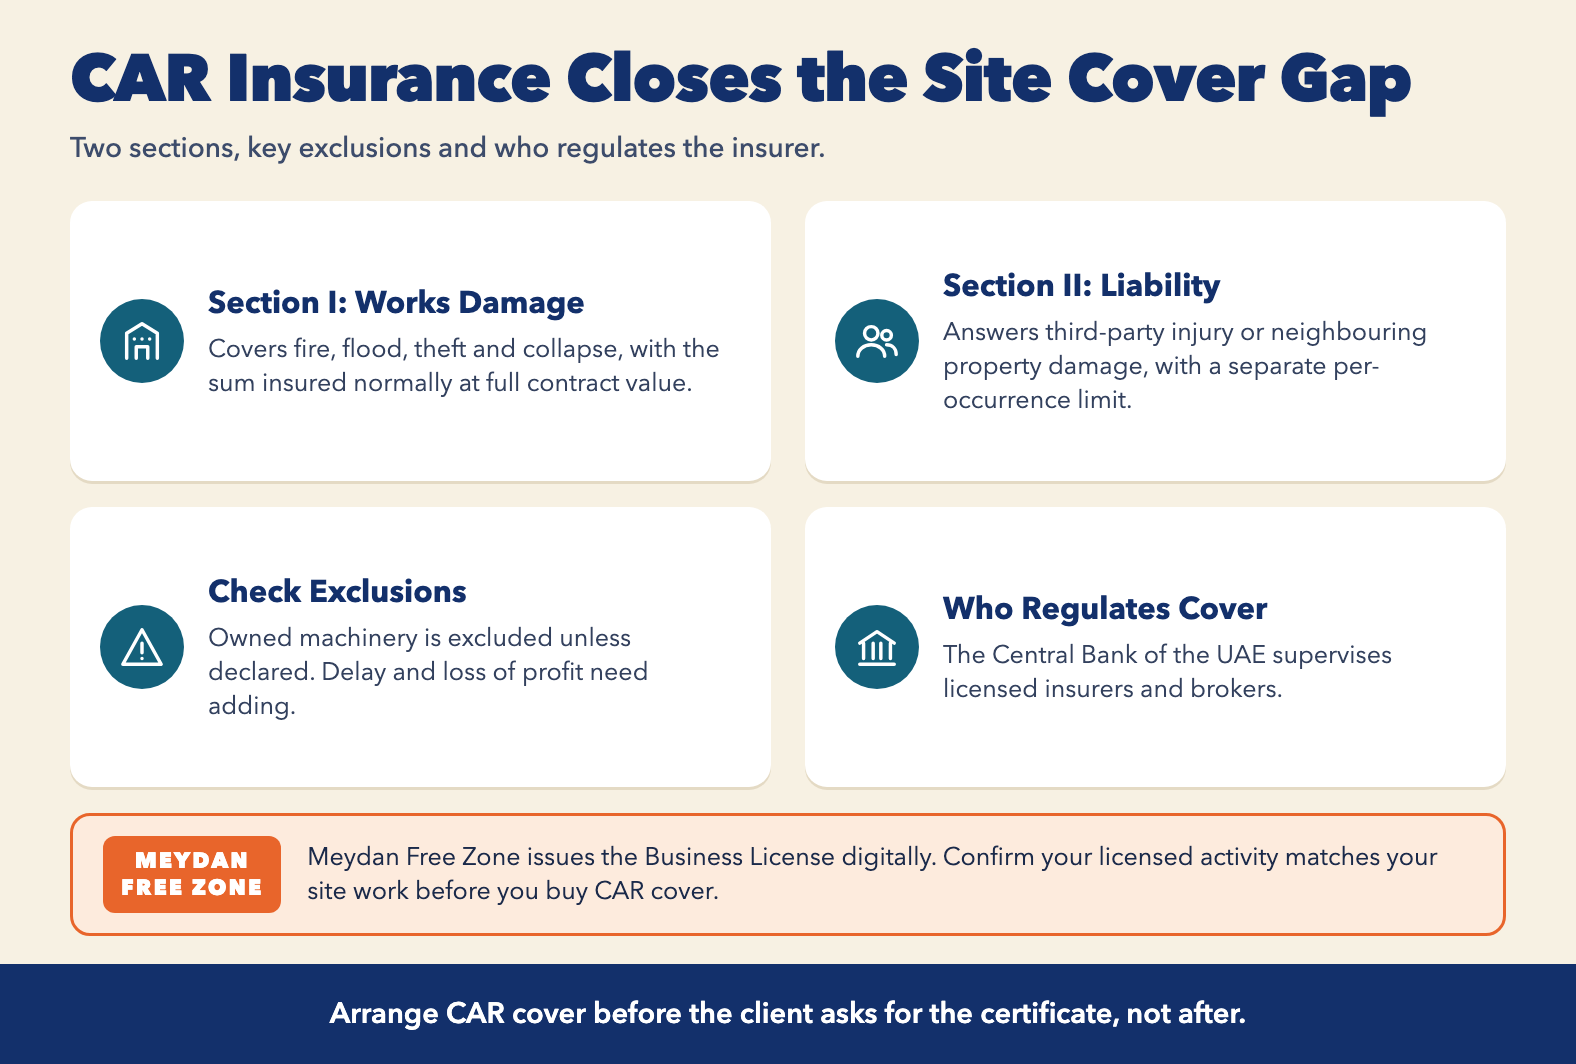
Insurance companies in the UAE are regulated at federal level by the Central Bank of the UAE, which took over insurance supervision from the former Insurance Authority. You buy CAR cover from a licensed insurer, directly or through a licensed broker. Clients, lenders and the contract add their own requirements.
Federal Supervision of Insurers
The Central Bank of the UAE supervises licensed insurers and brokers. Confirm the insurer's licensed status before you accept a quotation or pay any premium.
Contract and Authority Requirements
Main contracts and project approvals often require evidence of CAR cover before site mobilisation. Developers and emirate-level construction authorities set project conditions, so check the authority for each site. In practice, a developer may refuse site access until a subcontractor produces a valid certificate. Insurance clauses sit within UAE contract law, so read them as binding terms.
Who Needs a Policy and Who Pays for It
CAR cover is normally arranged by the main contractor, though the contract can make the project owner responsible. Subcontractors are usually named as co-insured or must carry their own cover. The insurance clause decides who buys the policy, who pays the premium and who holds the deductible.
Main Contractor, Owner and Subcontractor Roles
A typical allocation has the main contractor insuring, the owner named as co-insured and the lender noted as an interested party. Say an MEP subcontractor joins the main policy and pays a share of the premium through its subcontract price. Contract conditions override assumptions.
Free Zone Companies Working on Construction Projects
A Meydan Free Zone company providing engineering or consultancy services can still face contract-driven insurance duties. A consultancy may be asked for evidence of cover in a supervision contract. Your licensed activity must match the services you deliver, and site work is governed by the project's contract and the relevant emirate authority. A construction engineering services license in Dubai is one example of an activity that fits this work.
What Drives the Premium and Policy Terms
The CAR premium depends on contract value, project type, location, construction period, contractor experience, deductible level and claims history. Insurers price each project individually, so quotations are estimates until underwriting is complete. Premiums are quoted in AED and are generally subject to VAT.
Pricing Factors Underwriters Review
- Contract value and duration.
- Project type and site conditions.
- Level of subcontracting.
- Deductible: higher lowers premium but raises retained risk.
Two projects of equal value can price differently if one involves deep excavation. Treat any figure before underwriting as indicative.
Deductibles, Limits and Maintenance Period
The deductible applies per claim and appears in the policy schedule. A maintenance period extension covers the defects liability phase, for example 12 months if your contract requires it. VAT on premium follows Federal Tax Authority rules.
How to Arrange Cover
To arrange CAR cover, confirm the contract's insurance clause, gather project details, request quotations through a licensed insurer or broker, compare terms and exclusions, issue the policy before site start, and give the certificate to the client. Review cover after any change in scope or programme.
Step 1: Read the Insurance Clause
Identify the required sections, limits, named insureds and deductibles. A clause may require the client as co-insured with a waiver of subrogation, which stops the insurer pursuing that party after paying a claim.
Step 2: Prepare Project Details and Request Quotes
Assemble the contract value, programme, site address, method statements and subcontractor list. Then compare quotations on terms, not only price. In one typical case, three quotations differed mainly on exclusions and deductible.
Step 3: Issue the Policy Before Mobilisation
Cover must start on or before site possession. Provide the certificate of insurance to the client. Notify the insurer of variations and extensions, as a programme extension left unreported can create a gap in cover.
CAR Insurance Compared With Other Business Policies
Contractors all risk insurance protects the project and third parties during construction, while general liability, professional indemnity and workmen's compensation cover separate exposures. You typically need several policies together, because CAR does not replace employee, design or ongoing business cover.
Side-by-Side Comparison
| Feature | Contractors All Risk | General or Professional Liability |
|---|---|---|
| Main purpose | Protects one construction project and its third parties | Protects ongoing business operations or advice |
| Policy duration | Site start to handover, plus optional maintenance period | Usually annual and renewable |
| Covers physical damage to works | Yes, under Section I | No |
| Covers third-party injury or damage | Yes, arising from the project works | General liability: yes, for business operations |
| Covers design or advice errors | No, unless separately added | Professional liability: yes |
CAR Versus General and Professional Liability
The table above shows the split. A design-and-build contractor holding CAR but no professional indemnity is exposed on the design element. Gaps appear when founders assume one policy covers everything.
Other Policies Often Required on Site
- Workers' compensation and medical insurance for staff.
- Plant and machinery cover.
- Marine cargo cover for imported materials.
Imported steel, for example, is covered in transit by cargo cover and on site by CAR.
What CAR Cover Means for a Meydan Free Zone Company
For a Meydan Free Zone company, the first step is to confirm the licensed activity matches your site work, then budget CAR cover as a recurring project cost. Meydan Free Zone issues the Business License digitally after registration, and mAccounting offers bookkeeping and VAT registration support.
Match the License Activity to Site Work
Insurers and clients check that the work performed falls within the licensed activity. An insurer may query a claim that follows work outside the licensed scope.
Budget Premium and Keep Records Straight
Add the premium to your tender price instead of absorbing it later. mAccounting offers bookkeeping, VAT registration support and Corporate Tax support, which help keep project costs traceable. The Cost Calculator shows your license and setup costs, so you can add insurance on top.
Free Business Setup Cost Calculator
Calculate NowConclusion
Contractors all risk insurance in the UAE is a contract and balance sheet decision, not a formality. Read the insurance clause, confirm your licensed activity matches the work, and request comparable quotations from licensed insurers. With Meydan Free Zone, the Business License is issued digitally, so it is ready to share with insurers and clients once you register.
Ready to Launch Your Business in Dubai?
Let's Connect