Table of Contents
Frequently Asked Questions
Does a small company in the UAE have to record its office lease on the balance sheet?
It depends on the reporting framework. A company preparing full IFRS financial statements must recognise a right-of-use asset and a lease liability for its office lease. A company that reports under IFRS for SMEs follows different lease rules and does not apply IFRS 16 in the same way. Lenders, investors or auditors often decide which framework you use.
How do you calculate the lease liability for a warehouse rented in Dubai?
The lease liability is the present value of unpaid lease payments over the lease term. Discount the payments at the rate implicit in the lease, or at your incremental borrowing rate if that rate cannot be determined. Fixed payments and index-linked payments are included, while turnover-based rent is excluded.
Can a short-term warehouse rental be expensed instead of capitalised?
Yes. A lease of 12 months or less with no purchase option can be expensed on a straight-line basis. The exemption is applied by class of underlying asset and must be used consistently. A seasonal storage unit rented for a few months is a typical example.
Which discount rate should a tenant use when the landlord does not disclose one?
Use the incremental borrowing rate. This is the rate the tenant would pay to borrow, over a similar term and with similar security, the funds needed to obtain an asset of similar value. Keep the rate calculation on file, because auditors will ask for support.
How does lease accounting affect Corporate Tax in the UAE?
UAE Corporate Tax under Federal Decree-Law No. 47 of 2022 starts from accounting net profit. Under IFRS 16, depreciation and interest replace a flat rent expense, so expense is higher in early years and lower later. The total expense over the lease is unchanged. Corporate Tax applies at 9% on taxable income above AED 375,000.
Is VAT on rent included in the lease liability?
Recoverable VAT is excluded from the lease liability. VAT is accounted for on the landlord's invoice under normal VAT rules, and a VAT-registered tenant reclaims input VAT in the usual way. Keep invoices aligned with the lease schedule so the two records reconcile.
What happens to the accounting after a rent increase or lease extension?
A change in lease term or in payments requires the lease liability to be remeasured. The adjustment is generally recorded against the right-of-use asset. A fixed annual increase already stated in the contract is included in the original measurement, so it does not trigger remeasurement.
Does Ejari registration decide the lease term used in the accounts?
No. Ejari registers a Dubai tenancy contract, but the accounting term is based on the contract and your intentions. It covers the non-cancellable period plus any renewal options you are reasonably certain to exercise. A tenant that has renewed a one-year lease consistently may need to use a longer term, and should document that judgement for the auditor.
Topic Summary
What IFRS 16 in the UAE Means for Lessees
IFRS 16 requires a lessee to recognise most leases on the balance sheet. A company renting an office or warehouse records a right-of-use asset and a lease liability instead of expensing rent only. It has applied since 1 January 2019.
How Office and Warehouse Leases Are Measured
At commencement, the lease liability is the present value of unpaid lease payments, discounted at the implicit rate or your incremental borrowing rate. The right-of-use asset starts at that liability, plus direct costs, prepaid rent and restoration estimates, less incentives received.
Lease Terms That Change the Numbers
Lease term, renewal options, payment structure and exemptions drive the result. Leases of 12 months or less and low-value assets can be expensed. Reasonably certain renewal options extend the measured term, raising both asset and liability.
Steps to Account for a New Lease
To account for a new lease under IFRS 16, identify the lease, set the term, list the payments and choose the discount rate. Then calculate the liability, record the asset, and depreciate it and unwind interest each month.
Corporate Tax and VAT Effects of Lease Accounting
UAE Corporate Tax starts from accounting net profit under IFRS, so lease depreciation and interest flow into taxable income. The rate is 9% on taxable income above AED 375,000. VAT on rent is accounted for on the invoice, not through the lease liability.
IFRS 16 in the UAE Versus Expensing Rent
Under IFRS 16, rent becomes a liability and an asset, raising reported debt and EBITDA while lowering early-year profit. Expensing rent keeps the balance sheet lighter. Cash rent paid is identical either way.
What This Means for a Meydan Free Zone Company
A Meydan Free Zone company applies IFRS 16 if it prepares IFRS financial statements for audit, lenders or investors. Meydan Free Zone's mAccounting pillar offers bookkeeping, VAT registration support, Corporate Tax support and financial audit reports, which helps keep lease schedules and records consistent.
IFRS 16 Lease Accounting for UAE Office and Warehouse Leases
An office or warehouse lease is rarely just a rent line. Founders sign a multi-year lease, pay quarterly cheques and assume the books show only rent expense. IFRS 16 says otherwise for any entity preparing IFRS accounts, not just large groups. This guide explains how the right-of-use asset and lease liability are measured, where Corporate Tax and VAT intersect, and what it means for a Meydan Free Zone company.
What IFRS 16 in the UAE Means for Lessees
IFRS 16 requires a lessee to recognise most leases on the balance sheet. A company renting an office or warehouse records a right-of-use asset and a lease liability instead of expensing rent only. It has applied since 1 January 2019.
The Core Rule in Plain Terms
IFRS 16 replaced IAS 17 and removed the operating versus finance lease split for tenants. Your rent obligation becomes a liability. Your right to use the premises becomes an asset. A trading company signing a five-year Dubai warehouse lease must show both from commencement.
Who Has to Apply It
Any entity preparing IFRS financial statements applies it, including those required by lenders, investors or auditors. Small companies may use IFRS for SMEs, which doesn't follow the same lease model. Under Ministerial Decision No. 114 of 2023, that option is open to Corporate Tax payers with revenue of AED 50 million or less. An SME whose bank asks for full IFRS accounts will need to apply IFRS 16. The Capital Market Authority (formerly the Securities and Commodities Authority) oversees listed-market reporting, but the standard isn't limited to listed groups.
How Office and Warehouse Leases Are Measured
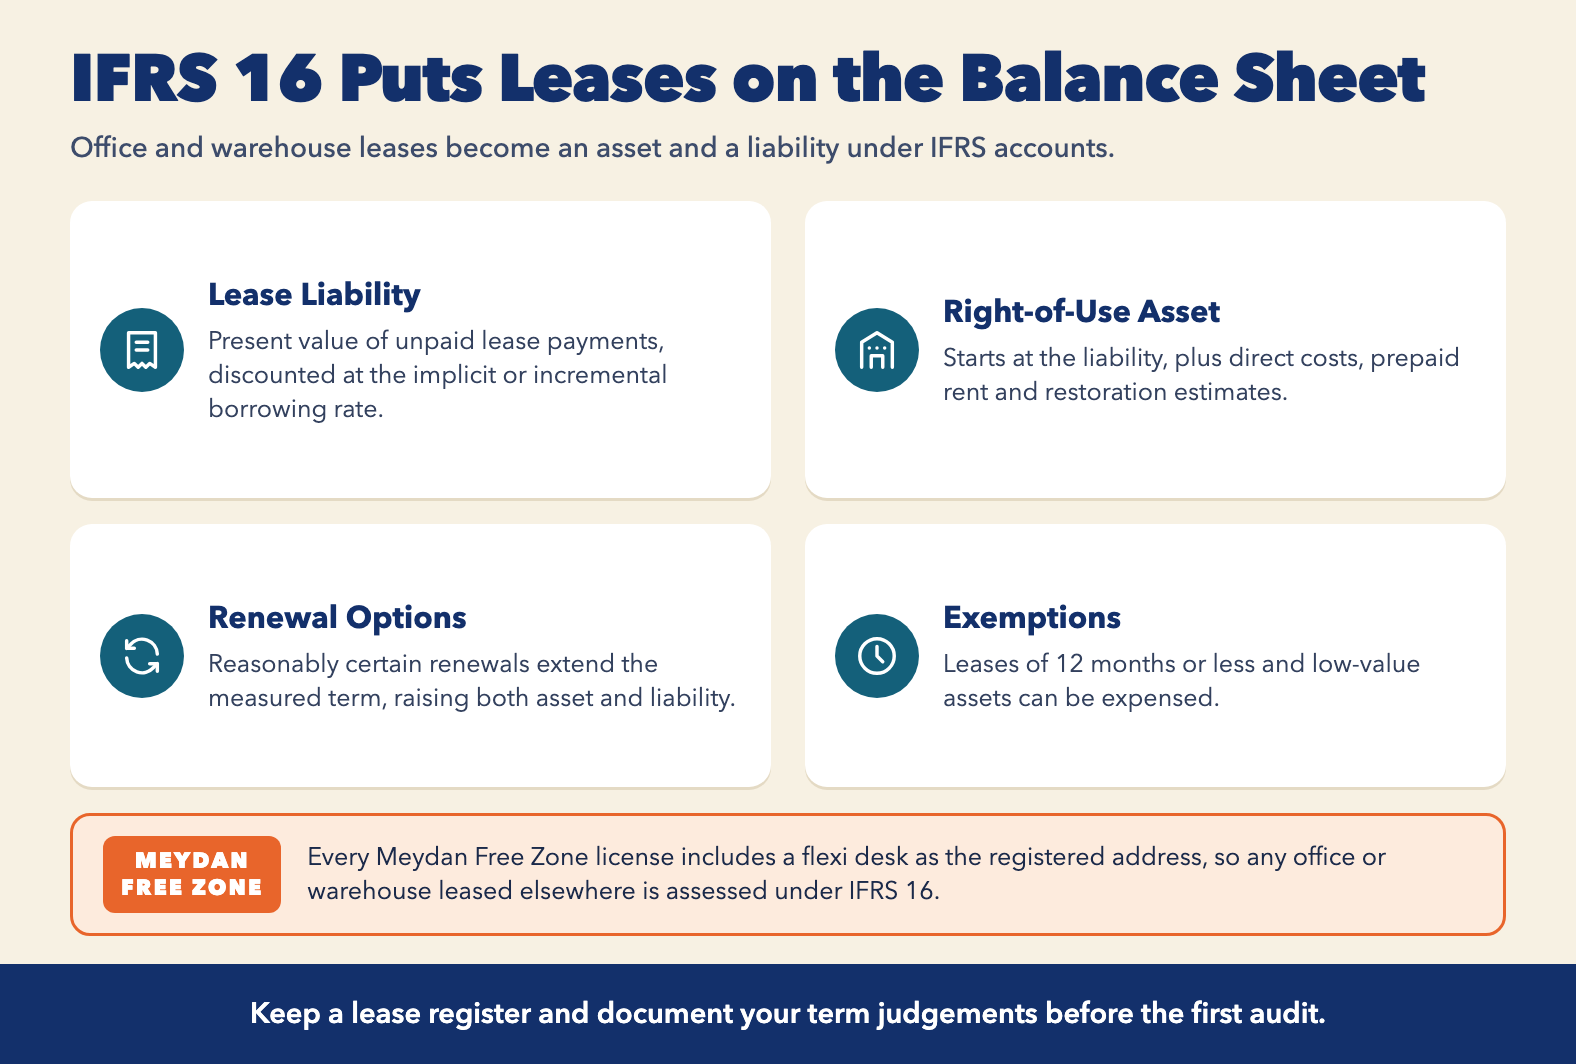
At commencement, the lease liability is the present value of unpaid lease payments, discounted at the implicit rate or your incremental borrowing rate. The right-of-use asset starts at that liability, plus direct costs, prepaid rent and restoration estimates, less incentives received.
Lease Liability and Discount Rate
- Include fixed payments over the lease term.
- Use the incremental borrowing rate if the implicit rate is unknown.
- Include index-linked payments; exclude turnover-based rent.
Take a three-year office lease with annual rent paid in four cheques. Each cheque is discounted to its present value, and the total becomes the opening liability.
Right-of-Use Asset and Depreciation
The asset depreciates straight-line over the shorter of the lease term or useful life. Interest on the liability is front-loaded, so early-year cost is higher. Warehouse fit-out restoration obligations are added to asset cost. Before signing, read four warehouse rental truths that could save your business in Dubai.
Lease Terms That Change the Numbers
Lease term, renewal options, payment structure and exemptions drive the result. Leases of 12 months or less and low-value assets can be expensed. Reasonably certain renewal options extend the measured term, raising both asset and liability.
Renewal Options and Ejari Registration
For Dubai mainland premises, Ejari registers the tenancy, but the accounting term rests on the contract and your intent. A tenant on a one-year Dubai lease it has renewed for years may need a longer term. Document that judgement for your auditor, and check the UAE contract law clauses that govern renewal and break rights.
Short-Term and Low-Value Exemptions
- Leases of 12 months or less, with no purchase option, qualify.
- Expense them straight-line.
- Apply the choice consistently by asset class.
A seasonal storage unit rented for a few months fits this.
Rent-Free Periods and Escalations
Incentives reduce the right-of-use asset. Fixed escalations sit inside lease payments. A warehouse lease with two rent-free months and a fixed annual increase is measured on the full schedule, not on cash paid in year one.
Steps to Account for a New Lease
To account for a new lease under IFRS 16, identify the lease, set the term, list the payments and choose the discount rate. Then calculate the liability, record the asset, and depreciate it and unwind interest each month.
Step 1: Confirm the Contract Contains a Lease
- Check there's an identified asset.
- Confirm you control its use.
- Test the landlord's substitution rights; a right to relocate you from shared warehouse space may mean no lease exists.
Step 2: Determine Term, Payments and Rate
- Take the non-cancellable period plus reasonably certain options.
- List fixed and index-linked payments, such as quarterly cheques.
- Record how you chose the discount rate.
Step 3: Record and Update the Entries
- Debit the asset and credit the liability.
- Book monthly depreciation and interest. In an illustrative AED 300,000 liability at 6%, month-one interest is AED 1,500.
- Remeasure after a term or payment change.
Corporate Tax and VAT Effects of Lease Accounting
UAE Corporate Tax starts from accounting net profit under IFRS, so lease depreciation and interest flow into taxable income. The rate is 9% on taxable income above AED 375,000. VAT on rent is accounted for on the invoice, not through the lease liability.
Accounting Profit as the Tax Starting Point
Federal Decree-Law No. 47 of 2022 uses accounting income as the base. Depreciation and interest replace straight rent expense. Early-year cost in a five-year lease runs higher than flat rent, but total expense over the lease is unchanged. Timing shifts, nothing more.
VAT on Rent Stays on the Invoice
The lease liability excludes recoverable VAT. VAT registration is mandatory once taxable supplies exceed AED 375,000 over 12 months. A registered tenant reclaims input VAT on warehouse rent under normal Federal Tax Authority rules. Keep invoices aligned with your lease schedule. The UAE tax compliance guide covers the wider lifecycle.
IFRS 16 in the UAE Versus Expensing Rent
Under IFRS 16, rent becomes a liability and an asset, raising reported debt and EBITDA while lowering early-year profit. Expensing rent keeps the balance sheet lighter. Cash rent paid is identical either way.
Effect on Ratios and Covenants
Higher liabilities lower your current ratio. EBITDA rises because rent moves below the line. A company renegotiating a facility after recording a large warehouse lease should confirm covenant definitions with the lender first. The Central Bank of the UAE regulates the banks you'll be dealing with.
Rent Expensing Compared With IFRS 16 Treatment
| Feature | Expensing Rent | IFRS 16 Treatment |
|---|---|---|
| Balance sheet | No lease asset or liability | Right-of-use asset and lease liability shown |
| Income statement | Flat rent expense each year | Depreciation plus front-loaded interest |
| EBITDA | Reduced by full rent | Higher, as rent sits below EBITDA |
| Cash rent paid | Unchanged | Unchanged, split into principal and interest |
| Typical lease scope | Leases of 12 months or less, low-value items | Multi-year office and warehouse leases |
What This Means for a Meydan Free Zone Company
A Meydan Free Zone company applies IFRS 16 if it prepares IFRS financial statements for audit, lenders or investors. Meydan Free Zone's mAccounting pillar offers bookkeeping, VAT registration support, Corporate Tax support and financial audit reports, which helps keep lease schedules and records consistent.
Where Your Lease Sits in the Records
A workspace or warehouse lease needs a lease schedule, not just a rent ledger. A trading company leasing external warehouse space should keep a lease register for its auditor. Decide the reporting framework before the first audit.
Questions to Settle Before Signing
- What are the term, renewal and break clauses?
- Who bears VAT and restoration costs?
- Does a short flexible term beat a longer, cheaper rate?
Every Meydan Free Zone license includes a flexi desk that serves as the registered address. Any office or warehouse you lease elsewhere is a separate contract to assess under IFRS 16.
Free Business Setup Cost Calculator
Calculate NowConclusion
IFRS 16 in the UAE turns a lease from a rent line into a measured asset and liability. Execution matters more than theory. A lease register, documented term judgements and consistent journals keep auditors, banks and the Federal Tax Authority aligned.
Review your current and planned leases, decide your reporting framework, and set up a lease schedule before the next reporting date. A Meydan Free Zone company can use mAccounting's bookkeeping support to keep that schedule alongside its other records.
Ready to Launch Your Business in Dubai?
Let's Connect