
Table of Contents
Frequently Asked Questions
Do directors of a free zone company need personal liability insurance?
D&O insurance is not generally a legal requirement for directors of a free zone company. It is a commercial decision based on exposure. Directors of companies with investors, co-directors, regulated activities or employees face more risk, so cover is more worth considering in those cases.
What is the difference between D&O insurance and professional indemnity?
D&O insurance protects directors and managers against claims about their management decisions, such as alleged mismanagement or breach of duty. Professional indemnity covers errors in advice or services delivered to clients. A consultancy often needs both, because client errors and board-level claims are different risks.
Can a company pay for its directors' D&O premiums in the UAE?
Yes, a company can usually buy the policy and pay the premium on behalf of its directors and managers. Side A cover responds directly to individuals when the company cannot indemnify them. Side B reimburses the company when it does indemnify them. Confirm the structure with your broker and the policy wording.
Does D&O cover regulatory fines and penalties?
Usually not. Most policies cover the cost of defending a regulatory investigation but exclude the fines and administrative penalties themselves, particularly where the law prevents them from being insured. Check how the wording treats penalties, and whether defence costs sit inside or outside the limit.
Who is classed as an insured person under a D&O policy?
An insured person normally includes directors, managers and officers, both current and past. Depending on the wording, shadow or de facto directors may also be covered. The policy definition decides this, so share your Memorandum and Articles of Association and list of management roles with the broker.
What does a claims-made policy mean for a director who resigns?
A claims-made policy responds to claims first made during the policy period and notified to the insurer. A director who resigns can still face a claim about earlier decisions. Cover for them depends on run-off or retroactive terms, so confirm these before binding the policy.
Do small companies with one shareholder need D&O cover?
Often less so. A sole-owner company with no outside investors, co-directors or regulated activity has fewer people who can bring a claim. Exposure still exists through creditors, tax and regulatory matters, and employment obligations, so assess these before deciding to go without cover.
What details does an insurer ask for before quoting D&O cover?
Insurers typically ask for the company's licensed activity, turnover, headcount, ownership structure and the names of directors and managers. They also ask about prior claims, known circumstances and the limit and retention you want. Premiums are individually quoted, so any figure is indicative until the insurer confirms it.
Topic Summary
What D&O Insurance in the UAE Is and Who It Covers
D&O insurance in the UAE is a liability policy that protects directors, managers and officers against claims arising from decisions made in their management role. It typically pays legal defence costs and, where permitted, damages or settlements. It covers individuals first, and sometimes the company itself.
Where Personal Liability Arises for UAE Directors
Directors and managers in the UAE can face personal liability for breach of duty, mismanagement, tax and regulatory non-compliance, employment obligations and company law breaches. Exposure depends on the legal form, the licensing authority and the federal laws that apply. Limited liability protects shareholders more reliably than it protects managers.
What a D&O Policy Covers and Excludes
A D&O policy usually covers defence costs, settlements and regulatory investigation costs arising from wrongful acts in a management role. It excludes fraud, deliberate misconduct, bodily injury, property damage and personal profit. Those losses fall under other policies, so check how the wording defines a wrongful act.
Regulation and Policy Placement in the UAE
The Central Bank of the UAE regulates insurance, and you must place policies with licensed insurers or through licensed intermediaries. D&O cover is a negotiated commercial product. Wording, limits and jurisdiction clauses vary.
How to Arrange D&O Cover in Three Steps
To arrange D&O insurance in the UAE, list management roles, assess exposure, engage a licensed broker, compare quotes, review the wording, then bind and diarise renewal.
Cost Factors and Compliance Mechanics
D&O premiums depend on company size, sector, turnover, claims history, limit and retention. Each premium is individually quoted, so no standard price exists. Treat it as a recurring cost and review it at each renewal alongside other compliance spending.
What This Means for a Founder's Decision
Consider D&O insurance in the UAE when your company has investors, co-directors, regulated activities, employees or external contracts. A sole-owner company with no outside stakeholders may need it less. Weigh who could realistically bring a claim before deciding.
D&O Insurance in the UAE: Cover for Directors and Managers
Many founders assume a limited liability company shields them completely from personal exposure, but directors and managers can still face personal claims, regulatory inquiries and defence costs. Directors' and officers' (D&O) insurance exists for that gap. This guide explains what it covers, where personal liability arises and how to decide whether your company needs it.
What D&O Insurance in the UAE Is and Who It Covers
D&O insurance in the UAE is a liability policy that protects directors, managers and officers against claims arising from decisions made in their management role. It typically pays legal defence costs and, where permitted, damages or settlements. It covers individuals first, and sometimes the company itself.
Core Definition and Policy Purpose
The policy responds to decisions and omissions in a management role. It is separate from cover for the business's own operations. Say a manager is named in a shareholder claim over a disputed investment. The policy funds the defence.
Who Counts as an Insured Person
- Directors, managers and officers.
- Shadow and de facto directors, depending on wording.
- Past and future directors, through run-off or retroactive terms.
A founder who resigns as manager can still face a claim over earlier decisions.
Three Coverage Parts Explained
- Side A: individuals, when the company can't indemnify them.
- Side B: reimbursement to the company for indemnifying them.
- Side C: entity cover, usually for listed companies.
If a company in distress can't indemnify its manager, Side A responds.
Where Personal Liability Arises for UAE Directors
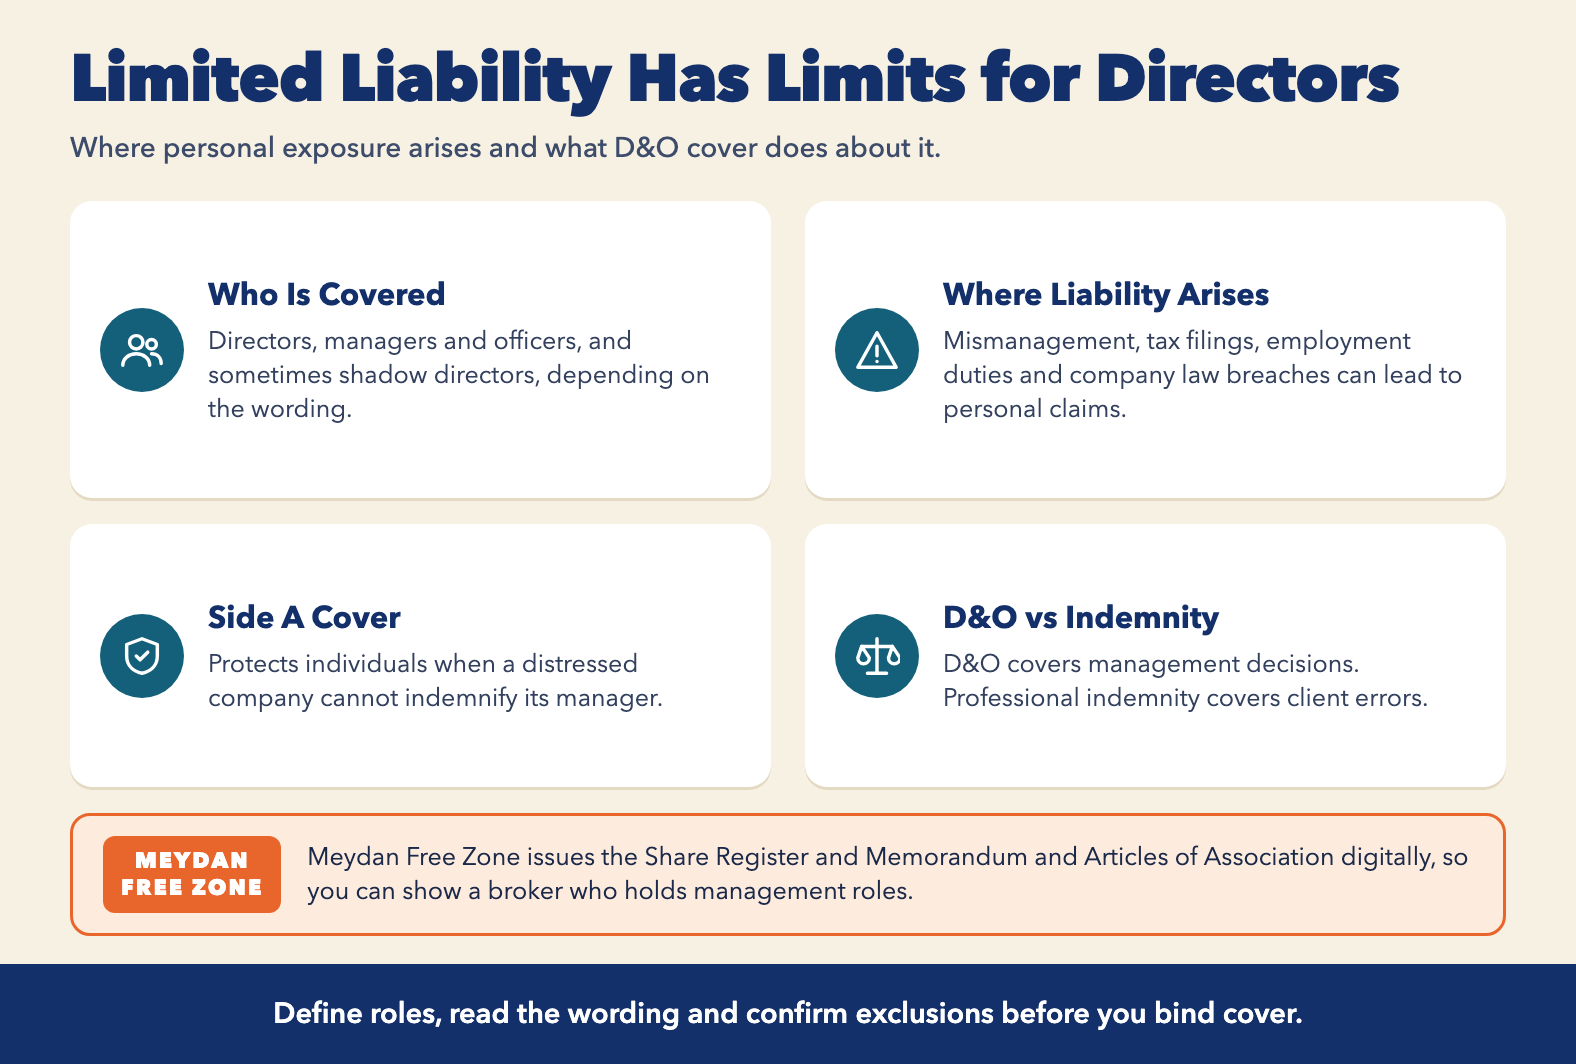
Directors and managers in the UAE can face personal liability for breach of duty, mismanagement, tax and regulatory non-compliance, employment obligations and company law breaches. Exposure depends on the legal form, the licensing authority and the federal laws that apply. Limited liability protects shareholders more reliably than it protects managers.
Company Law and Duty-Related Claims
For mainland companies, shareholders or the company can bring mismanagement claims under Federal Decree-Law No. 32 of 2021 on Commercial Companies. That law does not apply in Meydan Free Zone. There, the free zone's own regulations and the company's Articles of Association set out managers' duties, so confirm the position with a legal adviser. Picture a minority shareholder alleging that a manager approved a related-party payment without consent. A written shareholders' agreement that defines each manager's authority makes such claims easier to defend.
Tax, Regulatory and Employment Exposure
- Federal Tax Authority (FTA) penalties for late VAT or Corporate Tax filings.
- Questions about which individual was responsible.
- Employer labour obligations.
- Capital Market Authority duties for listed companies.
Repeated late filings lead to administrative penalties and scrutiny of who signed off. See penalties for non-compliance in the UAE for the wider picture.
Insolvency and Creditor Claims
Claims often surface as a company nears insolvency. A creditor may challenge transactions made shortly before trading stops. Fraud and wrongful trading allegations are common, and policies usually exclude deliberate acts.
What a D&O Policy Covers and Excludes
A D&O policy usually covers defence costs, settlements and regulatory investigation costs arising from wrongful acts in a management role. It excludes fraud, deliberate misconduct, bodily injury, property damage and personal profit. Those losses fall under other policies, so check how the wording defines a wrongful act.
Typical Inclusions
- Legal defence costs.
- Settlements and judgments, where insurable.
- Regulatory investigation costs.
- Emergency cost advances.
Common Exclusions
- Fraud, after final adjudication.
- Bodily injury and property damage.
- Claims known before inception, such as one notified to a previous insurer.
- Insured versus insured claims, with carve-backs.
D&O Versus Other Liability Policies
A consultancy needs professional indemnity for client errors and D&O for board-level claims. Read general liability vs professional liability in the UAE to see where those policies stop.
| Feature | D&O Insurance | Professional or General Liability |
|---|---|---|
| Who is protected | Directors, managers and officers personally | The business, for its services or premises |
| Typical trigger for a claim | A management decision or omission | A client error or third-party injury or damage |
| Usual claim types | Shareholder disputes, regulatory inquiries, creditor claims | Negligent advice, injury on premises, property damage |
| Common exclusions | Fraud, bodily injury, known prior claims | Management decisions, deliberate acts |
| Best suited to | Companies with investors or several directors | Service providers and businesses with public footfall |
Regulation and Policy Placement in the UAE
The Central Bank of the UAE regulates insurance, and you must place policies with licensed insurers or through licensed intermediaries. D&O cover is a negotiated commercial product. Wording, limits and jurisdiction clauses vary.
Who Regulates Insurers and Brokers
This isn't a free zone licensing matter. Check that your broker holds a valid license before placing cover.
Local Versus International Placement
Local insurers may reinsure with international markets. Check governing law, jurisdiction, currency and claims handling. A group with overseas directors needs worldwide jurisdiction wording.
How to Arrange D&O Cover in Three Steps
To arrange D&O insurance in the UAE, list management roles, assess exposure, engage a licensed broker, compare quotes, review the wording, then bind and diarise renewal.
- Map roles and exposure. A trading company lists two directors and a general manager, then records regulated activities, staff numbers and any prior claims.
- Engage a licensed broker and compare quotes. Request the same limits from several insurers. Compare retention, exclusions and whether defence costs sit inside the limit. Two similar premiums can differ on regulatory investigation cover.
- Review wording and bind. Check the definitions of wrongful act and insured person, plus the retroactive date. If you add a director mid-term, notify the insurer in writing.
Cost Factors and Compliance Mechanics
D&O premiums depend on company size, sector, turnover, claims history, limit and retention. Each premium is individually quoted, so no standard price exists. Treat it as a recurring cost and review it at each renewal alongside other compliance spending.
What Drives the Premium
- Sector, turnover and headcount.
- Limit of indemnity and retention.
- Claims history and governance quality.
A regulated services firm will pay more than a small holding company with one manager.
Renewals, Notifications and Record-Keeping
Policies run on a claims-made basis, so notify promptly. A late notification can mean a declined claim. Keep board minutes and approvals, and disclose changes in ownership or activity.
What This Means for a Founder's Decision
Consider D&O insurance in the UAE when your company has investors, co-directors, regulated activities, employees or external contracts. A sole-owner company with no outside stakeholders may need it less. Weigh who could realistically bring a claim before deciding.
When Cover Is Worth Prioritising
- Outside investors or minority shareholders.
- Several directors with shared authority.
- Regulated or contract-heavy activity.
A two-founder company with an angel investor should place cover after the first funding round.
How a Meydan Free Zone Structure Fits
Meydan Free Zone issues the Business License, Certificate of Formation, Share Register and Memorandum and Articles of Association digitally. These documents define who holds management roles, and a broker will ask to see them. mAccounting offers bookkeeping, VAT registration support and Corporate Tax support, which can reduce filing-related exposure. The policy itself comes from a licensed insurer regulated by the Central Bank of the UAE.
Free Business Setup Cost Calculator
Calculate NowConclusion
D&O insurance in the UAE protects the individuals who run a company, not just the company. It works best alongside clear governance, accurate filings and a written shareholders' agreement. Define roles, read the wording and confirm exclusions before you bind cover. With Meydan Free Zone, your Share Register and Memorandum and Articles of Association are issued digitally, ready to share with a broker.
Ready to Launch Your Business in Dubai?
Let's Connect