Table of Contents
Frequently Asked Questions
Is takaful only for Muslim business owners in the UAE?
No. Takaful is a commercial insurance product open to any individual or company, regardless of faith. Non-Muslim founders often choose it after comparing contribution levels, exclusions and surplus terms against conventional quotes. The decision is a pricing and policy-terms comparison, not a religious one.
Who regulates takaful companies operating in the UAE?
The Central Bank of the UAE licenses and supervises insurance and takaful operators nationwide. Takaful operators must also work under a Sharia governance framework, with a Sharia Supervisory Board approving products and investments. Medical insurance in Dubai is additionally governed by the Dubai Health Authority.
What happens to surplus money in a takaful fund?
If the participants' risk fund ends the period with money left after claims, reinsurance costs and reserves, part of the surplus may be returned to participants. Distribution rules differ by operator and must be stated in the policy terms. They are also subject to the Sharia board's rulings, so read the surplus clause before signing.
Can a company use takaful for employee medical insurance?
Yes, where the operator offers a health takaful product that meets the requirements of the relevant authority. Medical cover obligations depend on the emirate and visa type. A Meydan Free Zone company can compare takaful and conventional medical plans when arranging cover for residency visa holders through mResidency.
Does takaful cover the same risks as conventional insurance?
Largely, yes. Takaful operators in the UAE offer general takaful such as property, motor, marine and liability, plus health and family takaful. The wording, exclusions and claims process look similar, so compare each policy's terms line by line instead of assuming equivalence.
Is takaful cheaper than conventional business insurance?
Not necessarily. Contributions depend on the risk, the operator and the policy terms, so takaful can be higher, lower or equal to a conventional premium. The potential surplus return is a separate feature that may affect net cost over time, but it is not guaranteed. Request side-by-side quotes for the same cover.
What is the role of a Sharia board in takaful?
A Sharia Supervisory Board reviews and approves the operator's products, contract structures, investment choices and treatment of surplus. Its purpose is to confirm that the operator's activities follow Sharia principles. Product documents should state that the board has approved the takaful product.
Can a free zone company buy takaful cover?
Yes. A Meydan Free Zone company can buy takaful from operators licensed in the UAE, as it would any other insurance. After registration, Meydan Free Zone issues the Business License digitally, and the policy certificate can be kept with the company records. Insurance is not included in the license itself.
Topic Summary
What Takaful Insurance in the UAE Is
Takaful is a Sharia-compliant form of insurance in which participants contribute to a shared fund that pays claims for members who suffer a covered loss. A takaful operator manages the fund for a fee. Takaful insurance in the UAE is overseen by the Central Bank of the UAE and each operator's Sharia board.
How a Takaful Policy Works
A takaful policy splits each contribution into a participants' risk fund and an operator fee. Claims and reinsurance costs are paid from the fund. If the fund ends the period in surplus, part of it may be returned, depending on the operator's approved terms. The same structure applies whichever emirate you operate in.
Steps to Arrange Takaful Insurance in the UAE
To arrange takaful cover, list the risks your business carries and confirm which are mandatory. Then request quotes from licensed operators, compare contributions, exclusions and surplus terms, and check Sharia board approval before the policy is issued. Keep the schedule with your licensing and banking records. A broker can help, and the guide to starting an insurance brokers business shows how that activity is licensed.
Regulation of Takaful Insurance in the UAE
The Central Bank of the UAE licenses and supervises insurance and takaful operators nationwide. Takaful companies also operate under a Sharia governance framework. Health insurance in Dubai is additionally regulated by the Dubai Health Authority, so check which authority governs each class of cover.
Takaful vs Conventional Insurance for Businesses
Takaful runs on shared contributions and mutual guarantee, with a segregated fund and possible surplus returns. Conventional insurance transfers risk to an insurer for a premium it keeps. Cover and claims handling can look similar, so the real differences lie in fund structure, surplus and governance.
Business Lines Covered by Takaful in Dubai
Takaful operators in the UAE offer general takaful (property, motor, marine, liability), plus health and family takaful. Which lines suit a business depends on its assets, staff and agreements. Match each exposure to a policy instead of buying a bundle by default.
What Takaful Means for a Meydan Free Zone Company
A Meydan Free Zone company can buy takaful from licensed UAE operators like any other insurance. After registration, Meydan Free Zone issues the Business License digitally, and mResidency supports residency visas, Emirates ID and medical insurance. Takaful is one option to compare for staff medical cover. If your plans involve selling cover yourself, setting up an insurance business is a separate licensing question.
Takaful Insurance for UAE Businesses: How It Works
Most UAE businesses need insurance in their first year, from medical cover for visa holders to cover for stock, vehicles or liability. Many founders assume takaful is a religious preference with weaker protection, or conventional insurance with a different label, and neither view holds up.
This guide explains how takaful works, how it differs from conventional cover, who regulates it and how to compare quotes for your business.
What Takaful Insurance in the UAE Is
Takaful is a Sharia-compliant form of insurance in which participants contribute to a shared fund that pays claims for members who suffer a covered loss. A takaful operator manages the fund for a fee. Takaful insurance in the UAE is overseen by the Central Bank of the UAE and each operator's Sharia board.
Cooperative Risk Sharing Explained
Participants pool contributions to cover each other's losses. The operator administers the fund but does not own the risk the way a conventional insurer does. Picture a logistics SME and ten other participants paying into a motor fleet fund. A claim by one is paid from the shared pool.
Why Founders Misread Takaful
Takaful is not limited to Muslim customers. It is a commercial product with policy documents, a claims process and cover limits you can compare. A non-Muslim trading company might choose it because surplus sharing suits its clean claims record. That is a pricing decision, not a faith one.
How a Takaful Policy Works
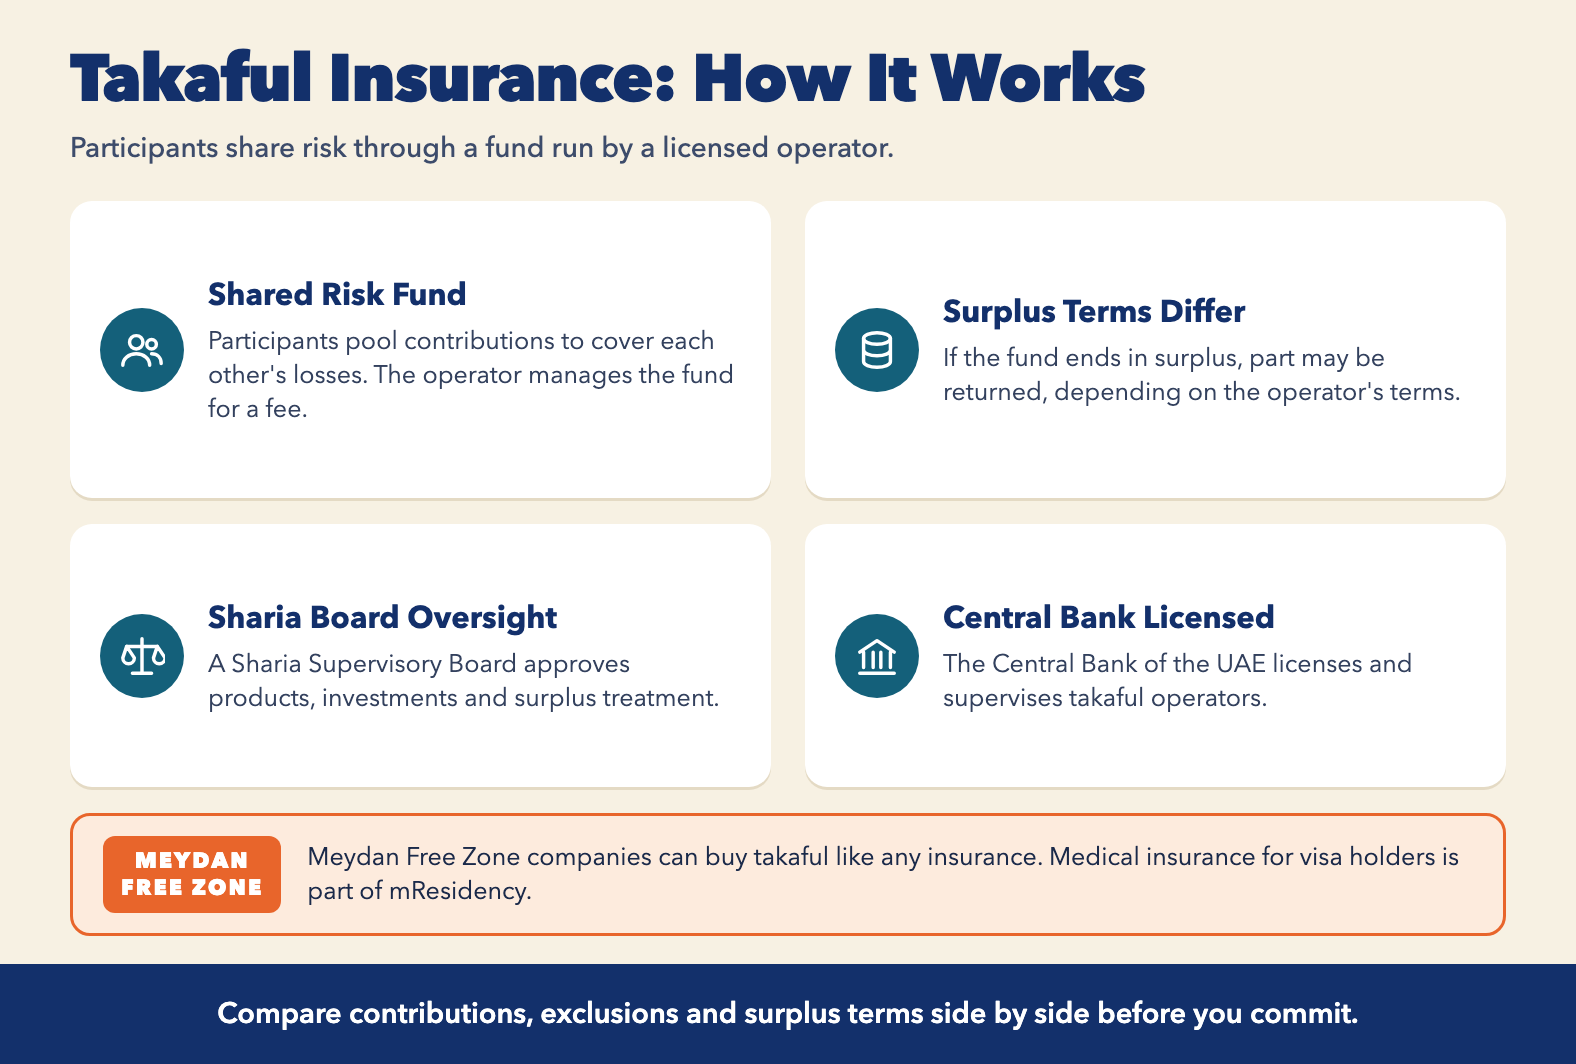
A takaful policy splits each contribution into a participants' risk fund and an operator fee. Claims and reinsurance costs are paid from the fund. If the fund ends the period in surplus, part of it may be returned, depending on the operator's approved terms. The same structure applies whichever emirate you operate in.
Contributions and the Risk Fund
- Documents say "contribution", not "premium".
- The risk fund is kept separate from shareholder funds.
- The operator charges a management fee (wakala) or shares investment profit (mudaraba).
- Your policy schedule should show the wakala percentage and the amount allocated to the fund.
Surplus, Deficit and Sharia Oversight
Surplus rules differ by operator and must be written into the policy. Say a founder receives two quotes for the same office cover: one returns surplus to participants, the other retains it for the fund. Same cover, different economics. If the fund runs a deficit, the operator typically provides an interest-free loan (qard hasan) to it. A Sharia Supervisory Board approves products, investments and surplus treatment.
Steps to Arrange Takaful Insurance in the UAE
To arrange takaful cover, list the risks your business carries and confirm which are mandatory. Then request quotes from licensed operators, compare contributions, exclusions and surplus terms, and check Sharia board approval before the policy is issued. Keep the schedule with your licensing and banking records. A broker can help, and the guide to starting an insurance brokers business shows how that activity is licensed.
Step 1: Map Your Mandatory and Optional Risks
- Separate required cover, such as medical insurance for visa holders, from commercial cover.
- List stock, goods in transit, office contents, fleet and staff.
- Note liability exposure from your service or product.
Step 2: Compare Licensed Operators
- Use only operators licensed by the Central Bank of the UAE.
- Compare three quotes line by line: contribution, deductible, exclusions, claims process, surplus terms.
- Ask for takaful and conventional quotes side by side.
Step 3: Confirm Terms and Issue the Policy
- Read the surplus and deficit clauses before signing.
- Confirm Sharia board approval appears in the product documents.
- File the certificate with company records for bank and landlord requests.
Regulation of Takaful Insurance in the UAE
The Central Bank of the UAE licenses and supervises insurance and takaful operators nationwide. Takaful companies also operate under a Sharia governance framework. Health insurance in Dubai is additionally regulated by the Dubai Health Authority, so check which authority governs each class of cover.
Federal Supervision by the Central Bank
Insurance activity is now governed by Federal Decree-Law No. 6 of 2025, which replaced the 2023 insurance law and keeps insurers and takaful operators under Central Bank of the UAE licensing and supervision. Operators must hold a license to underwrite and manage takaful funds. Complaints go to the operator first; if it is not resolved, ask how to escalate it under Central Bank rules.
Emirate-Level Health Rules in Dubai
The Dubai Health Authority sets medical insurance requirements for the emirate. Employer obligations depend on the emirate and visa type, so confirm the current requirements before you arrange visas. For plan comparisons, see this guide to the best health insurance for business owners.
Takaful vs Conventional Insurance for Businesses
Takaful runs on shared contributions and mutual guarantee, with a segregated fund and possible surplus returns. Conventional insurance transfers risk to an insurer for a premium it keeps. Cover and claims handling can look similar, so the real differences lie in fund structure, surplus and governance.
Structural Differences That Affect Cost
A services SME comparing liability quotes should ask how surplus is treated. That one clause can change the net cost of cover after a clean year.
Side-by-Side Comparison
| Feature | Takaful | Conventional Insurance |
|---|---|---|
| Risk model | Risk sharing among participants | Risk transfer to the insurer |
| Use of contributions or premiums | Paid into a segregated risk fund, less an operator fee | Becomes the insurer's revenue |
| Surplus treatment | May be returned to participants per policy terms | Retained by the insurer as profit |
| Governance | Regulator plus a Sharia Supervisory Board | Regulator and board of directors |
| Investment screening | Investments screened for Sharia compliance | No Sharia screening required |
Where Takaful Fits Banking and Supply Agreements
Some landlords, lenders or counterparties prefer Sharia-compliant cover. Say a supply agreement requires it: takaful satisfies that clause. It does not guarantee bank approval or better terms. Match the cover to the written requirement, not to assumptions.
Business Lines Covered by Takaful in Dubai
Takaful operators in the UAE offer general takaful (property, motor, marine, liability), plus health and family takaful. Which lines suit a business depends on its assets, staff and agreements. Match each exposure to a policy instead of buying a bundle by default.
General, Health and Family Takaful
- General: property, motor, marine and liability.
- Health: supports employer medical obligations.
- Family: life and protection needs.
A small import business might insure stock in transit and staff medical cover through takaful.
Matching Cover to Your Activity
Trading firms prioritise cargo and stock cover. Consultancies prioritise professional liability. Read exclusions before relying on any policy, because they decide what a claim actually pays.
What Takaful Means for a Meydan Free Zone Company
A Meydan Free Zone company can buy takaful from licensed UAE operators like any other insurance. After registration, Meydan Free Zone issues the Business License digitally, and mResidency supports residency visas, Emirates ID and medical insurance. Takaful is one option to compare for staff medical cover. If your plans involve selling cover yourself, setting up an insurance business is a separate licensing question.
Licensing First, Cover Second
Settle your activity and license before sizing cover. A single-shareholder founder can use Fawri, which issues a Business License online in under 60 minutes, then arrange cover. Keep policy certificates alongside the Certificate of Formation, Share Register and Memorandum and Articles of Association.
Medical Insurance Through mResidency
mResidency covers residency visas, the medical fitness test, Emirates ID, medical insurance, dependent visas and return permits. Compare takaful and conventional medical plans before applying for visas. Medical insurance is not included in the license itself.
Free Business Setup Cost Calculator
Calculate NowConclusion
Takaful insurance in the UAE is a regulated, commercial alternative to conventional cover. Its value lies in fund structure, surplus terms and Sharia governance, not the label. With Meydan Free Zone, medical insurance for visa holders is part of mResidency, so list your other risks and request side-by-side takaful and conventional quotes before committing.
Ready to Launch Your Business in Dubai?
Let's Connect