Table of Contents
Frequently Asked Questions
Can a UAE company claim credit for tax withheld by a foreign client?
Yes, where the income is included in the company's UAE taxable income and the foreign tax was legally due and paid. The credit reduces the UAE Corporate Tax on that same income. The company must hold evidence of the withholding, such as a certificate or payment receipt.
Is foreign tax refundable if it exceeds the UAE Corporate Tax on the same income?
No. The credit is limited to the lower of the foreign tax paid and the UAE Corporate Tax due on that income, and unused credit cannot be carried forward or back. For a company already above the AED 375,000 band, AED 200,000 of foreign income produces AED 18,000 of UAE tax at 9%. If AED 20,000 was withheld abroad, the credit stops at AED 18,000.
Do Qualifying Free Zone Persons benefit from a foreign tax credit?
Only on income taxed at 9%. Qualifying income is taxed at 0%, so there is no UAE tax to offset. A Meydan Free Zone company with non-qualifying income, such as an overseas fee outside the qualifying rules, may claim relief on that portion.
What proof of foreign tax paid should a business keep?
Keep withholding certificates, foreign tax assessments, payment receipts, and the contracts and invoices linking the tax to the income. Records must be available if the Federal Tax Authority asks for them. Request certificates from clients at the time of payment, not months later.
Does a Tax Residency Certificate reduce the tax foreign clients withhold?
It can. A Tax Residency Certificate helps a UAE company access treaty rates under a Double Taxation Agreement, which cap what the foreign country may withhold. Presenting it before payment can reduce the foreign tax, so less relief is needed later.
Where do you claim the credit when filing your Corporate Tax return?
You enter it in the relevant section of the Corporate Tax return, filed through the Federal Tax Authority's EmaraTax portal. The return and any net tax due are payable within nine months of the end of the financial year. Calculate the credit separately for each foreign income stream.
How should foreign tax be converted into AED for the calculation?
Convert foreign tax and foreign income into AED using a consistent exchange rate method applied for the tax period. Document the method and the rates used. Inconsistent conversion can distort the cap and invite questions on review.
Can an individual freelancer claim a foreign tax credit in the UAE?
The credit is a Corporate Tax relief, so it applies to taxable persons filing a Corporate Tax return. A freelancer operating through a licensed business may be within scope depending on their activity and turnover. Without a UAE Corporate Tax liability on the income, there is nothing to offset.
Topic Summary
Foreign Tax Credit Under UAE Corporate Tax Explained
A foreign tax credit is relief that reduces a UAE taxable person's Corporate Tax by the foreign tax already paid on the same income. It prevents double taxation of foreign-sourced income. The credit cannot exceed the UAE tax attributable to that income, and you must hold evidence of the foreign tax paid.
When Foreign Tax Credit Applies to UAE Businesses
A foreign tax credit is available when foreign-sourced income is included in UAE taxable income and tax was paid on it abroad. Typical cases are withholding on service fees, royalties, interest or dividends, and tax on a foreign permanent establishment's profits.
Limits and Calculation Rules for the Credit
The credit is the lower of the foreign tax paid and the UAE Corporate Tax due on the same income. Excess foreign tax is not refunded, and Article 47 does not allow unused credit to be carried forward or back. Because the cap follows the UAE tax on the relevant income, work it out for each foreign income stream.
How to Claim a Foreign Tax Credit in Your Corporate Tax Return
To claim the credit, register, collect proof, calculate the capped credit, enter it in your return on the FTA's EmaraTax portal, and file within nine months of your financial year end.
Common Mistakes When Claiming the Credit
The usual errors are claiming tax on income not taxed in the UAE, missing certificates, exceeding the cap, using the wrong exchange rate, and ignoring treaty rates. Each can cut or cancel the credit and prompt FTA questions.
Meydan Free Zone Companies and Foreign Tax Credit
A Meydan Free Zone company can use the foreign tax credit under UAE Corporate Tax only where income is taxable in the UAE. Qualifying income taxed at 0% leaves nothing to offset, while non-qualifying income taxed at 9% may support relief.
Conclusion
The foreign tax credit under UAE Corporate Tax is capped relief, not a refund. It works when income is taxable in the UAE, foreign tax is documented, and the calculation is done per stream. Before your next overseas contract, check whether withholding applies, whether a treaty rate is available, and whether the income will be taxed at 9%. In a Meydan Free Zone company, keep qualifying income apart from income taxed at 9%, because only the latter can carry a credit.
Foreign Tax Credit Under UAE Corporate Tax: How to Claim It
Most UAE founders assume zero personal income tax means foreign tax never touches their business. That changes when an overseas client pays you with tax already withheld, because the UAE's 9% Corporate Tax can apply to the same income. The question is how much of that foreign tax you can set against your UAE bill. This guide explains how the foreign tax credit works, where the cap sits and how to claim it in your return.
Foreign Tax Credit Under UAE Corporate Tax Explained
A foreign tax credit is relief that reduces a UAE taxable person's Corporate Tax by the foreign tax already paid on the same income. It prevents double taxation of foreign-sourced income. The credit cannot exceed the UAE tax attributable to that income, and you must hold evidence of the foreign tax paid.
What the Credit Does in Practice
The credit reduces the tax you owe, not your taxable income. That makes it stronger than a deduction. Say a UAE company earns consulting fees from a client abroad, and the client withholds tax at source. Those fees still enter UAE taxable income, taxed at 9% above AED 375,000. The credit offsets the UAE tax on them by the amount withheld, within the cap.
Foreign Tax Credit Outcomes by Income Type
| Feature | Taxed at 9% in the UAE | Taxed at 0% in the UAE |
|---|---|---|
| UAE tax to offset against | Yes, 9% of the attributable income | None, the UAE tax is nil |
| Credit available for foreign tax paid | Yes, up to the lower of foreign tax and UAE tax | No credit to claim |
| Impact of foreign withholding | Largely recovered up to the cap | Becomes a final cost |
| Evidence required | Withholding certificates and payment proof | Records still useful for treaty rate checks |
| Typical planning response | Track each income stream and tax paid | Seek treaty rates at source to cut withholding |
Legal Basis and Responsible Authority
The relief sits in Article 47 of Federal Decree-Law No. 47 of 2022 on the Taxation of Corporations and Businesses. The Federal Tax Authority (FTA) administers registration, returns and credit claims. The Ministry of Finance issues the supporting Cabinet and ministerial decisions.
Why It Matters for Founders With Overseas Clients
The UAE's 0% withholding tax rate on payments to non-residents does not remove foreign withholding tax charged by your client's country. Our UAE withholding tax guide covers that outbound versus inbound split. An unclaimed credit lifts your effective tax rate on foreign income.
When Foreign Tax Credit Applies to UAE Businesses
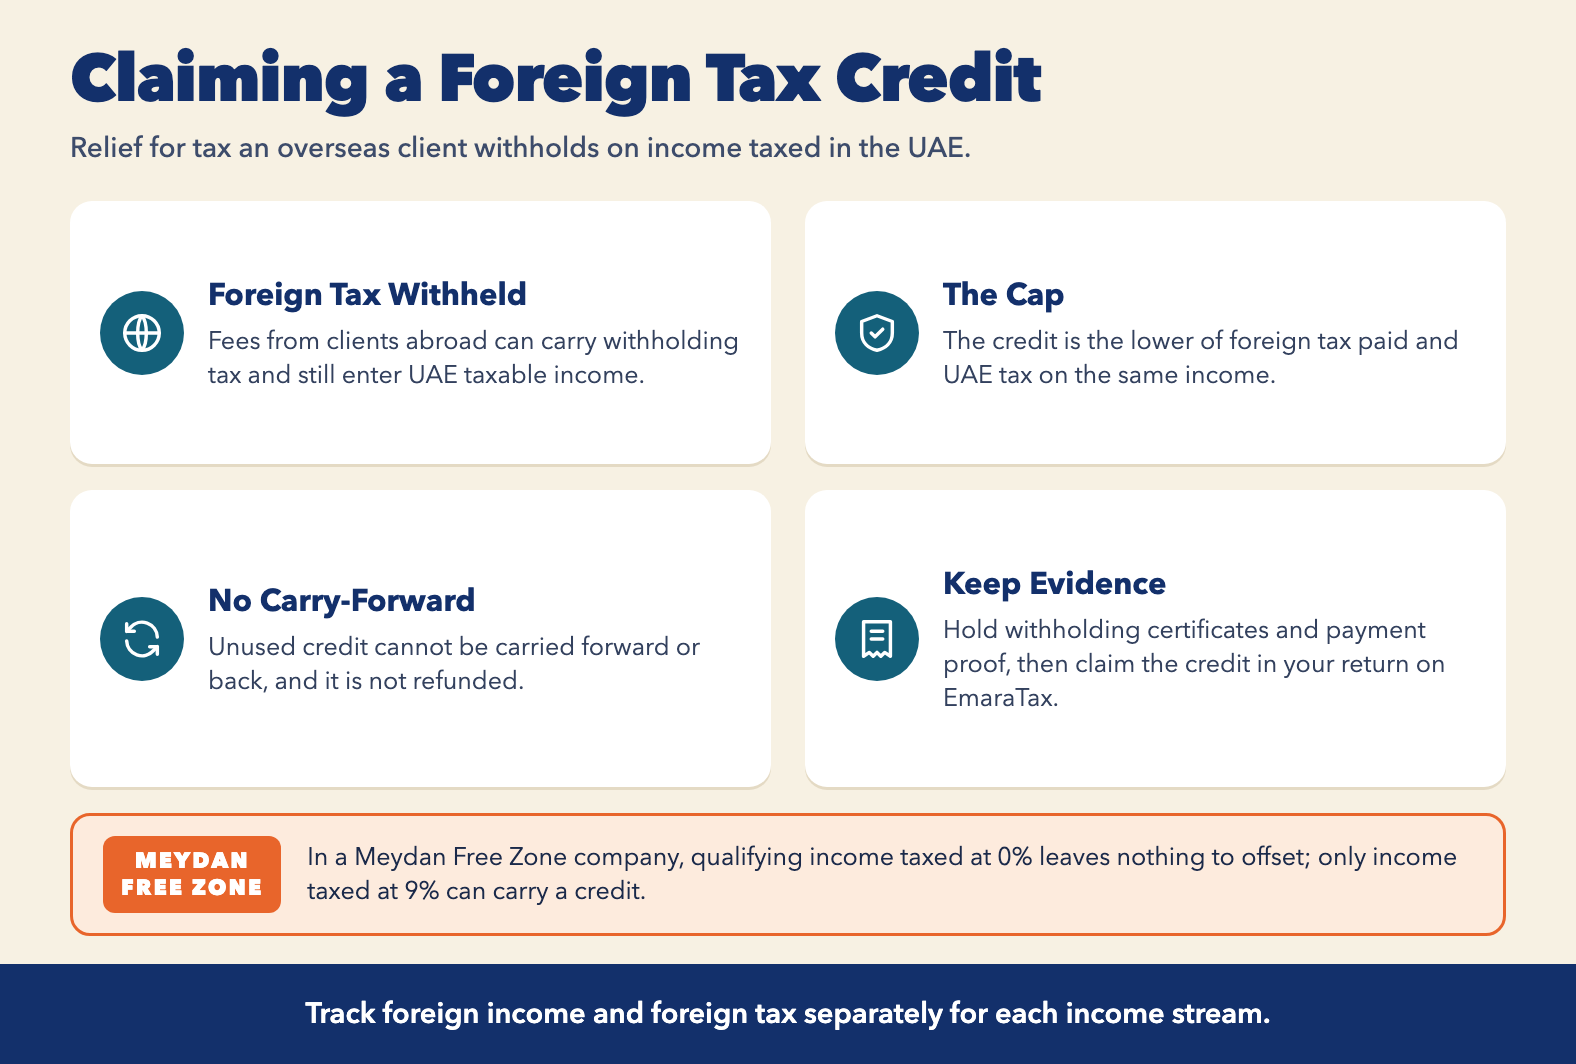
A foreign tax credit is available when foreign-sourced income is included in UAE taxable income and tax was paid on it abroad. Typical cases are withholding on service fees, royalties, interest or dividends, and tax on a foreign permanent establishment's profits.
Income Types That Commonly Qualify
- Service fees, royalties and interest taxed at source.
- Profits of a foreign permanent establishment.
- Dividends where the participation exemption does not apply.
Role of Double Taxation Agreements
Treaties cap the rate a foreign country can withhold. A UAE company can present its Tax Residency Certificate to the payer and ask for the treaty rate at source. That leaves less tax needing relief later. Our double tax treaty guide explains eligibility.
Income That Falls Outside the Credit
Income not taxed in the UAE gives you nothing to credit against. Qualifying Free Zone Person income taxed at 0% is the main example. Foreign tax that is refundable, or was not legally due, does not qualify either.
Limits and Calculation Rules for the Credit
The credit is the lower of the foreign tax paid and the UAE Corporate Tax due on the same income. Excess foreign tax is not refunded, and Article 47 does not allow unused credit to be carried forward or back. Because the cap follows the UAE tax on the relevant income, work it out for each foreign income stream.
The Cap on the Credit
Take a company whose other profits already exceed AED 375,000, and AED 200,000 of foreign income. UAE tax at 9% on that income is AED 18,000. If AED 20,000 was withheld abroad, the credit stops at AED 18,000 and AED 2,000 is lost. Expenses attributed to that income reduce the UAE tax, and so lower the cap.
Currency and Timing Considerations
Convert foreign tax into AED using one consistent rate for the tax period, and document the method. The foreign tax should relate to the same period, or be properly matched to it.
Unused Credits and Planning Points
- Unused credit cannot be carried forward or back, so it only helps in the same tax period.
- Negotiate gross-up clauses or treaty rates in contracts.
- Price overseas contracts with withholding leakage in mind.
How to Claim a Foreign Tax Credit in Your Corporate Tax Return
To claim the credit, register, collect proof, calculate the capped credit, enter it in your return on the FTA's EmaraTax portal, and file within nine months of your financial year end.
- Confirm registration and tax period. Register for Corporate Tax on EmaraTax and identify the financial year the return covers.
- Gather evidence. Collect withholding certificates, foreign assessments, payment receipts, and the contracts and invoices linking the tax to the income. Keep them for the legally required period.
- Calculate the capped credit. Work out UAE tax per foreign income stream, compare it with foreign tax paid, and take the lower figure.
- File and pay. Enter the credit in the relevant return section. Filing and payment of net tax are both due nine months after the financial year end.
Common Mistakes When Claiming the Credit
The usual errors are claiming tax on income not taxed in the UAE, missing certificates, exceeding the cap, using the wrong exchange rate, and ignoring treaty rates. Each can cut or cancel the credit and prompt FTA questions.
Documentation Gaps
A founder finds a client withheld tax across four invoices but holds one receipt. Only a quarter of the credit is supportable. Ask for the certificate when you are paid, not months later.
Treaty and Rate Errors
Without a residency certificate, a payer may apply the full domestic rate. You then bear tax a treaty would have reduced, and the credit cannot recover it beyond the cap.
Meydan Free Zone Companies and Foreign Tax Credit
A Meydan Free Zone company can use the foreign tax credit under UAE Corporate Tax only where income is taxable in the UAE. Qualifying income taxed at 0% leaves nothing to offset, while non-qualifying income taxed at 9% may support relief.
Qualifying and Non-Qualifying Income
Picture a company earning most income from qualifying activities, plus one overseas service fee with foreign tax withheld that falls outside qualifying income. That fee is taxed at 9%, so the credit matters there. Read our qualifying vs non-qualifying income guide before structuring contracts.
Records and Filing Support Through mAccounting
mAccounting, part of Meydan Plus, offers bookkeeping and Corporate Tax support, including Corporate Tax registration and return filing packages. Bookkeeping by income stream makes the credit calculation straightforward. It supports your records but does not guarantee a claim outcome.
Free Business Setup Cost Calculator
Calculate NowConclusion
The foreign tax credit under UAE Corporate Tax is capped relief, not a refund. It works when income is taxable in the UAE, foreign tax is documented, and the calculation is done per stream. Before your next overseas contract, check whether withholding applies, whether a treaty rate is available, and whether the income will be taxed at 9%. In a Meydan Free Zone company, keep qualifying income apart from income taxed at 9%, because only the latter can carry a credit.
Ready to Launch Your Business in Dubai?
Let's Connect