Table of Contents
Frequently Asked Questions
Is there VAT on buying a residential property in the UAE?
It depends on the sale. The first supply of a new residential building within three years of completion is zero-rated at 0%, so the buyer pays no VAT. Later resales and bare land sales are exempt, so no VAT is charged on those either. Commercial property sales carry the standard 5% rate.
Do tenants pay VAT on rent for a house or apartment?
No. A residential lease is an exempt supply, so a landlord should not charge VAT on rent for a home let as a residence. If a standard residential tenancy invoice shows a VAT line, ask the landlord to review the classification and issue a corrected invoice.
What is the difference between zero-rated and exempt residential property supplies?
Both result in no VAT charged to the buyer or tenant. The difference sits with the seller. A zero-rated seller, such as a developer making a first sale, can recover related input VAT. An exempt seller, such as a landlord, cannot recover it.
Can a landlord recover VAT on repairs to a rented apartment?
Generally no. Rent from a residential lease is exempt, and input VAT linked to exempt supplies is not recoverable. VAT paid on repairs, maintenance and agent fees therefore becomes a cost for the owner, which should be factored into the rental yield.
How is VAT charged on a serviced apartment or holiday home?
Short-term accommodation, including hotels, serviced apartments with hotel-style services and nightly lets, is standard-rated at 5%. A plain apartment let on a long-term residential tenancy is exempt. Whether hotel-style services are provided, and how the unit is used, decide the treatment.
What happens to VAT if a villa is converted into an office?
A change in use can move the property out of the residential category and into the commercial one, which is taxed at 5%. Owners should document the change and review their VAT position before treating later supplies as exempt.
Do owners of mixed-use buildings need to register for VAT?
Registration is mandatory when taxable supplies exceed AED 375,000 a year. In a mixed-use building, shop or office rent is taxable at 5%, while residential rent is exempt. Owners must apportion income and costs between the two parts and keep separate records.
Does a free zone company pay VAT on a residential purchase?
Free zone status does not change the VAT classification of the property. A first sale within three years of completion is zero-rated, and a resale is exempt, whether the buyer is a person or a company. Office space leased for the business is commercial and carries 5% VAT.
Topic Summary
What VAT on Residential Property in the UAE Means
Homes are treated differently from commercial space under Federal Decree-Law No. 8 of 2017 on VAT, which the Federal Tax Authority (FTA) administers. The first sale of a new residential building within three years of completion is zero-rated. Later sales and residential leases are exempt. Commercial property is taxed at the standard 5% rate.
VAT on Sale of Residential Property
The VAT on a home sale depends on timing. The first supply within three years of a building's completion is zero-rated at 0%. Any later sale is exempt. Bare land is also exempt. Commercial property sales carry 5% VAT, so the property's classification decides the invoice.
VAT on Residential Leases
A residential lease in the UAE is an exempt supply, so landlords charge no VAT on rent for a home let as a residence. Short-term accommodation such as hotels and serviced apartments is standard-rated at 5%. Commercial leases also carry 5% VAT, so the tenancy purpose decides the treatment.
Five Checks Before You Buy or Lease
Before buying or leasing, confirm the property type, the completion date, the seller's or landlord's VAT status, the intended use and the invoice details. These five checks show whether VAT is zero-rated, exempt or charged at 5%, and they prevent corrections after the transaction.
Cost and Compliance Risks for Owners
The main risk for an owner is irrecoverable input VAT. Exempt residential leases and resales do not allow recovery of related VAT, so it becomes a recurring cost. Owners also risk wrongly charging VAT or missing the registration obligation if taxable supplies exceed AED 375,000 a year.
What This Means for a Founder's Property Decision
For founders, VAT on residential property in the UAE affects the true cost of a home or investment property. Buyers of new homes pay no VAT, tenants of residential units pay none, and commercial space costs 5% more.
Conclusion
VAT on residential property in the UAE rewards precision. Zero-rating, exemption and the 5% rate each apply to specific facts, and the facts decide the cost. Confirm the property's classification, completion date and the counterparty's VAT status before committing. For a company licensed in Meydan Free Zone, the free zone address does not change how the property itself is classified, so keep exempt and taxable income in separate records from day one.
VAT on Residential Property in the UAE: Sales and Leases
Founders often assume every property deal in Dubai carries 5% VAT, whether they are buying a home, renting one or holding a unit through the company. It doesn't, and the difference changes the price you pay, the tax an owner can recover and the invoices you should expect. This guide covers VAT on residential sales and leases, the costs owners carry and the checks to run before you sign.
What VAT on Residential Property in the UAE Means
Homes are treated differently from commercial space under Federal Decree-Law No. 8 of 2017 on VAT, which the Federal Tax Authority (FTA) administers. The first sale of a new residential building within three years of completion is zero-rated. Later sales and residential leases are exempt. Commercial property is taxed at the standard 5% rate.
Zero-Rated Versus Exempt Supplies
Zero-rated means 0% VAT is charged, but the seller can still recover related input VAT. Exempt means no VAT is charged, and the seller cannot recover related input VAT. The buyer sees no VAT either way. The seller's position is very different.
Say a developer sells a new apartment: it charges no VAT but reclaims its construction VAT. A landlord leasing the same unit later cannot reclaim VAT on repairs. That gap drives developer pricing and landlord costs, not only the invoice you receive.
VAT Treatment of Residential and Related Property Transactions
| Transaction | VAT Treatment |
|---|---|
| First sale of a new residential building within three years of completion | Zero-rated (0%). The seller recovers input VAT. |
| Resale of residential property | Exempt. No VAT charged, and no input VAT recovery. |
| Bare land sale | Exempt. No VAT on the price. |
| Long-term residential lease | Exempt. Rent carries no VAT line. |
| Commercial or short-term accommodation lease | Standard-rated at 5%. |
What Counts as Residential
- A building designed for use as a residence, such as a villa or apartment.
- Hotels, serviced apartments and short-term stays are not residential for the exemption.
- Mixed-use buildings need an apportionment between residential and commercial parts.
A serviced apartment let with hotel-style services is standard-rated. A plain apartment let on a 12-month tenancy as a home is exempt.
VAT on Sale of Residential Property
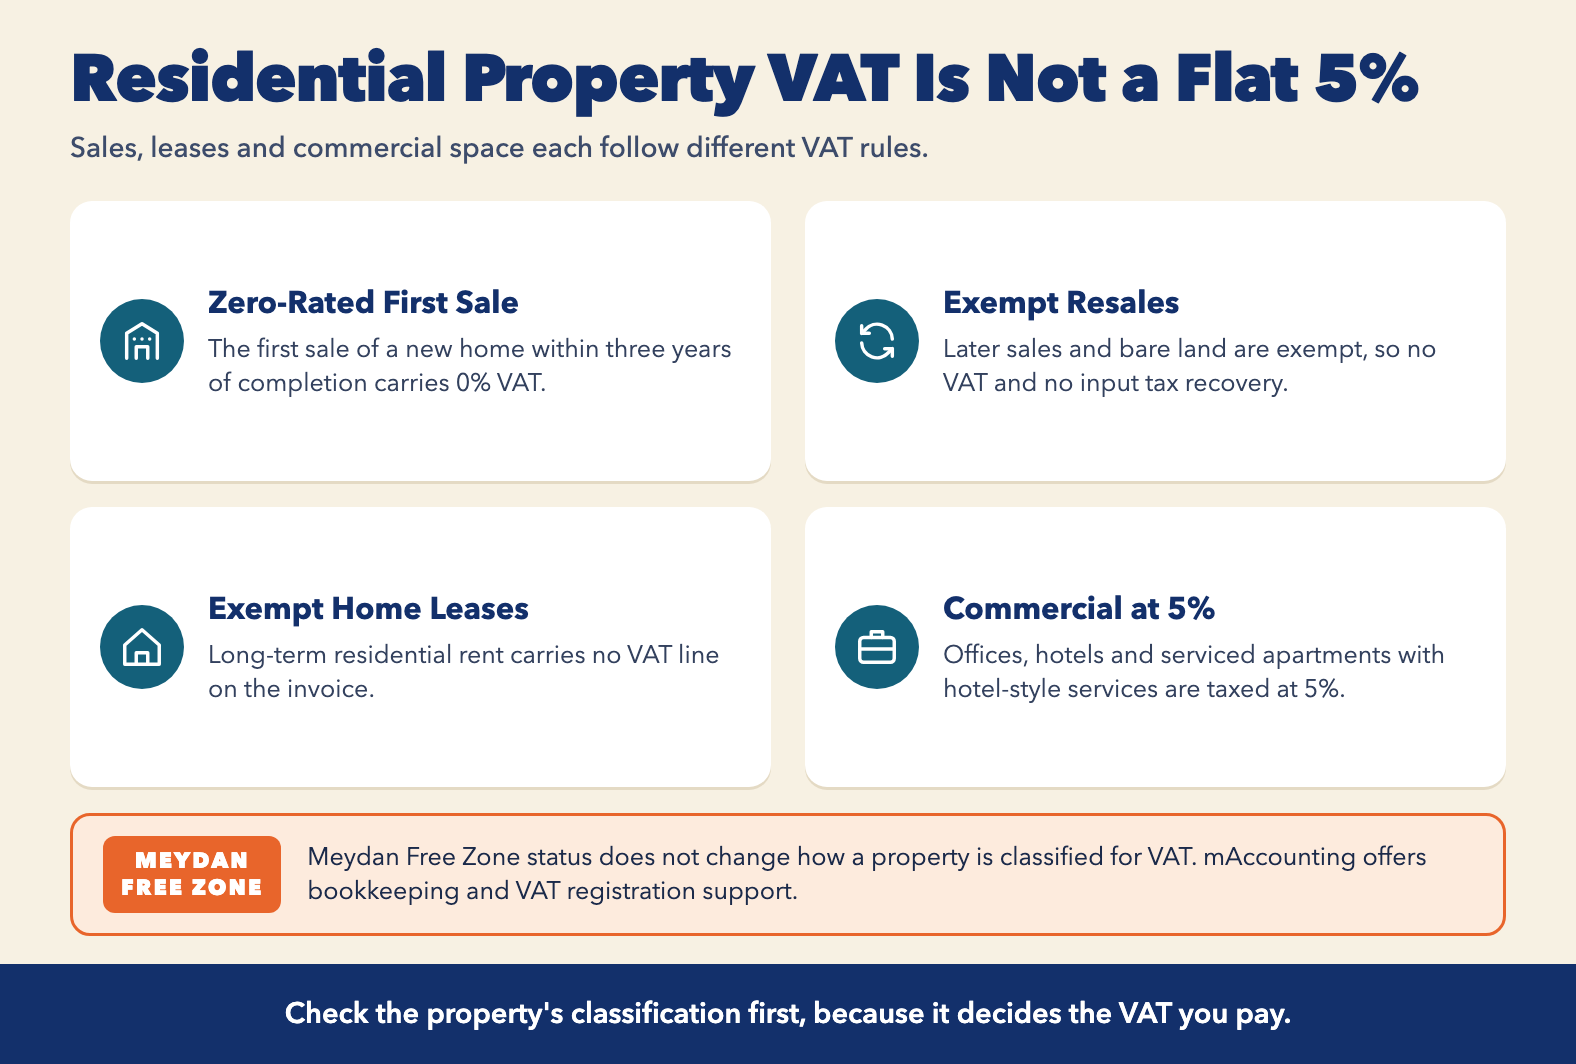
The VAT on a home sale depends on timing. The first supply within three years of a building's completion is zero-rated at 0%. Any later sale is exempt. Bare land is also exempt. Commercial property sales carry 5% VAT, so the property's classification decides the invoice.
First Sale From a Developer
A founder buys an off-plan apartment and pays no VAT on the price. The developer reclaims its construction input VAT. The three-year window runs from building completion, so the completion date matters.
Resale and Bare Land
Resale after the first supply is exempt, and so is bare land. Say an investor resells a villa after five years. No VAT is charged, but the investor cannot reclaim VAT on agent fees tied to the sale. Registered sellers still keep records of the exempt supply.
Converting Residential to Commercial Use
- A change in use can alter the VAT treatment.
- Document the change at the time it happens.
- Review your position with a tax adviser.
A villa converted into a consultancy office and let as commercial space is generally standard-rated at 5%.
VAT on Residential Leases
A residential lease in the UAE is an exempt supply, so landlords charge no VAT on rent for a home let as a residence. Short-term accommodation such as hotels and serviced apartments is standard-rated at 5%. Commercial leases also carry 5% VAT, so the tenancy purpose decides the treatment.
Long-Term Tenancies for Homes
A founder renting a two-bedroom apartment on a 12-month tenancy pays rent with no VAT line. The landlord cannot recover input VAT on related costs. You shouldn't be asked for VAT on a standard residential tenancy.
Short-Term and Staff Accommodation
- Hotel-style and serviced stays are standard-rated at 5%.
- Company-leased staff housing is a business cost.
- Check the lease purpose clause and the invoice before paying.
A company leasing a furnished unit nightly for visiting staff is invoiced 5% VAT.
Five Checks Before You Buy or Lease
Before buying or leasing, confirm the property type, the completion date, the seller's or landlord's VAT status, the intended use and the invoice details. These five checks show whether VAT is zero-rated, exempt or charged at 5%, and they prevent corrections after the transaction.
Confirm Classification and Completion Date
- Confirm whether the property is residential, commercial or mixed-use.
- Check the completion certificate to see if the three-year window applies.
Verify Status, Use and Documents
- Ask whether the seller or landlord is VAT registered.
- Confirm the intended use is stated in the lease or sale agreement.
- Review the invoice against UAE tax invoice requirements.
One founder spotted a VAT line on a residential lease invoice and asked the landlord to review it. A corrected invoice followed.
Cost and Compliance Risks for Owners
The main risk for an owner is irrecoverable input VAT. Exempt residential leases and resales do not allow recovery of related VAT, so it becomes a recurring cost. Owners also risk wrongly charging VAT or missing the registration obligation if taxable supplies exceed AED 375,000 a year.
Irrecoverable Input VAT
VAT on agent fees, maintenance and fit-out is a cost for an owner making exempt supplies. A landlord pays 5% VAT on a renovation, cannot reclaim it against exempt rent, and builds it into the annual cost. Zero-rated sellers can recover input VAT, so the two treatments are not equivalent. Budget for it in your rental yield.
Registration and Record-Keeping
- Registration is mandatory above AED 375,000 of taxable supplies a year. See the UAE VAT registration guide.
- Owners with mixed-use property must apportion income and costs.
- Where input VAT is recoverable, the VAT refund for companies process applies.
A company owning a mixed-use building tracks residential rent and shop rent separately to apportion VAT correctly.
What This Means for a Founder's Property Decision
For founders, VAT on residential property in the UAE affects the true cost of a home or investment property. Buyers of new homes pay no VAT, tenants of residential units pay none, and commercial space costs 5% more.
Personal Home Versus Company-Held Property
A Meydan Free Zone company holding property for investment faces exempt-supply rules on residential income. Offices used for the business are commercial and standard-rated. Free zone status does not change the VAT classification of the property itself. A founder who buys a resale apartment personally pays no VAT, then leases an office for the company at 5%.
Support From Meydan Free Zone
mAccounting, part of Meydan Plus, offers bookkeeping and VAT registration support. A company with mixed rental income can keep exempt and standard-rated income in separate ledgers.
Free Business Setup Cost Calculator
Calculate NowConclusion
VAT on residential property in the UAE rewards precision. Zero-rating, exemption and the 5% rate each apply to specific facts, and the facts decide the cost. Confirm the property's classification, completion date and the counterparty's VAT status before committing. For a company licensed in Meydan Free Zone, the free zone address does not change how the property itself is classified, so keep exempt and taxable income in separate records from day one.
Ready to Launch Your Business in Dubai?
Let's ConnectReferences
- Federal Tax Authority (FTA), UAE, VAT guidance on real estate and Federal Decree-Law No. 8 of 2017.