Table of Contents
Topic Summary
Place of Effective Management and UAE Corporate Tax Residency
Place of effective management is where a company's key management and commercial decisions are made in substance. Under UAE Corporate Tax, a foreign-incorporated company can become a UAE tax resident if its effective management and control sit in the UAE, whatever its country of incorporation. For a wider overview, see this UAE Corporate Tax explained guide.
How the Federal Tax Authority Treats Management and Control
The Federal Tax Authority looks at where strategic decisions are actually taken, not where meetings are recorded. Board decisions, director residence and the location of senior management all matter. A single factor rarely decides the outcome, so effective management and control in the UAE is judged on the overall pattern of how the company runs.
Foreign Company or UAE Company: How Residency Changes the Tax Position
A UAE tax resident company is taxed on worldwide income. A non-resident is taxed only on income linked to a UAE permanent establishment, UAE-sourced income and income from a UAE nexus. Corporate Tax is 0% on taxable income up to AED 375,000 and 9% above that, subject to each regime's conditions.
Three Checks to Test Your Company's Place of Effective Management
Test your company's position with three checks. Look at where directors live and decide, where board meetings happen, whether records match reality, who holds bank signing authority and where senior staff work. If most answers point to the UAE, treat the company as likely UAE tax resident.
Qualifying Free Zone Person and Residency
A free zone company is a UAE tax resident because it is incorporated in the UAE, and residency alone does not remove 0% treatment. A Qualifying Free Zone Person pays 0% on qualifying income if it meets conditions such as adequate substance. Non-qualifying income is taxed at 9%.
Tax Residency Certificates and Treaty Relief
A tax residency certificate is issued by the Federal Tax Authority and can support a double tax treaty claim. A UAE resident company can apply if it meets the authority's conditions. The certificate does not set the Corporate Tax position itself.
What This Means for a Meydan Free Zone Founder
A founder running a Meydan Free Zone company from the UAE should assume UAE tax residency and plan for registration, records and substance. Meydan Free Zone's mAccounting pillar offers bookkeeping, VAT registration support and Corporate Tax support, which helps keep the records these tests rely on.
Place of Effective Management: When a Company Is UAE Tax Resident
Many foreign founders assume a company registered abroad sits outside the UAE tax net, even when its directors live in Dubai and take every key decision there. That assumption can cause problems at bank reviews and at filing. Under UAE Corporate Tax, a foreign company that is effectively managed and controlled in the UAE is treated as UAE tax resident, whatever its registration says. This guide shows how that test works and how to check your own structure.
Place of Effective Management and UAE Corporate Tax Residency
Place of effective management is where a company's key management and commercial decisions are made in substance. Under UAE Corporate Tax, a foreign-incorporated company can become a UAE tax resident if its effective management and control sit in the UAE, whatever its country of incorporation. For a wider overview, see this UAE Corporate Tax explained guide.
How the Law Defines a Resident Person
Federal Decree-Law No. 47 of 2022 on the Taxation of Corporations and Businesses treats a juridical person created under UAE law, including a free zone company, as resident. A foreign-incorporated entity can also be resident if it is effectively managed and controlled in the UAE. Picture an offshore company whose sole director lives in Dubai and signs every contract from there. That company has a strong UAE link.
Why Incorporation Alone Does Not Decide Residency
Country of registration is one factor, not the test. Substance carries the weight. Take a trading company incorporated abroad but run day to day from a Dubai office: its UAE management may outweigh its foreign registration. Founders using holding structures often miss this.
How the Federal Tax Authority Treats Management and Control
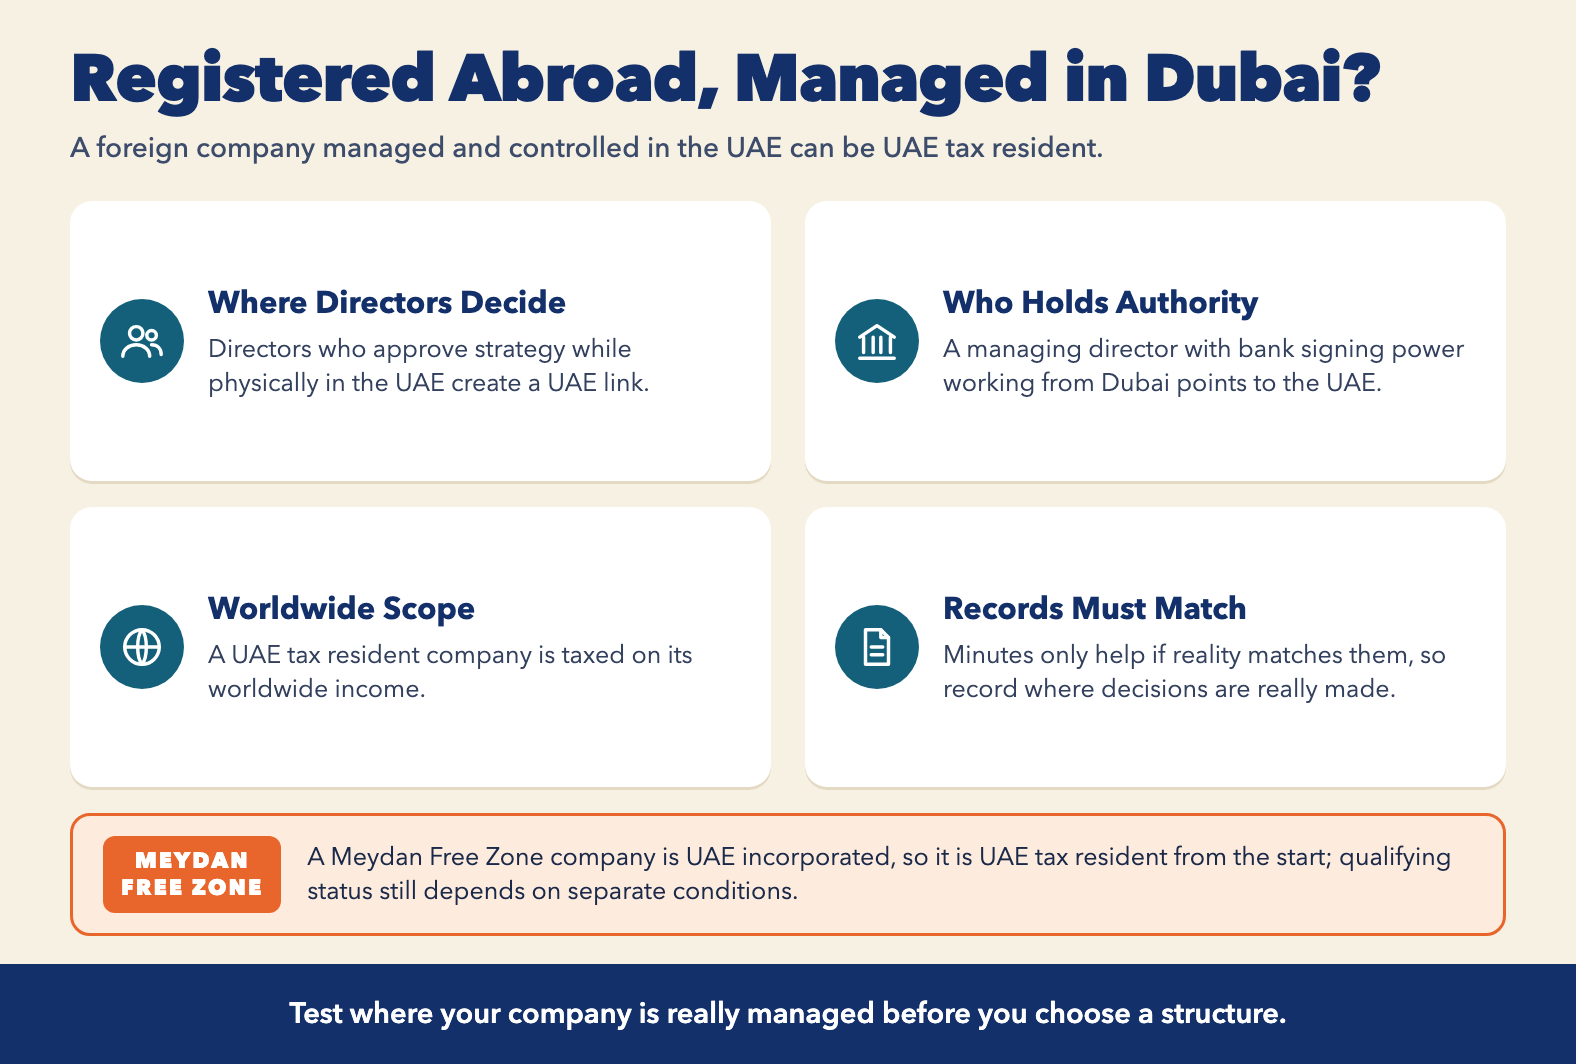
The Federal Tax Authority looks at where strategic decisions are actually taken, not where meetings are recorded. Board decisions, director residence and the location of senior management all matter. A single factor rarely decides the outcome, so effective management and control in the UAE is judged on the overall pattern of how the company runs.
Where Board Decisions Are Really Made
Minutes only help if reality matches them. A foreign board that meets once a year while a UAE-based founder decides everything else carries little weight. Directors who approve strategy while physically in the UAE create a UAE link.
Resident vs Non-Resident Company: UAE Corporate Tax Position
| Feature | UAE Tax Resident Company | Non-Resident Company |
|---|---|---|
| Basis of taxation | Worldwide income is in scope | UAE-sourced income and permanent establishment profits only |
| Registration with the Federal Tax Authority | Mandatory, followed by an annual return and financial statements | Required where a UAE permanent establishment or nexus exists |
| Treaty access through a residency certificate | Can apply to the Federal Tax Authority for a certificate | Cannot claim UAE residence under a treaty |
| Trigger for tax status | UAE incorporation, or effective management and control in the UAE | Foreign incorporation with management and control outside the UAE |
| Impact of UAE-based management | Supports residency and, in a free zone, the substance case | Can tip a foreign company into residency, so it needs review |
Who Holds Real Authority
- Signing power over contracts and bank accounts.
- Residence of the people who direct the business.
- Location of senior staff running key commercial functions.
A managing director with bank signing power who works from Dubai points firmly to the UAE.
Foreign Company or UAE Company: How Residency Changes the Tax Position
A UAE tax resident company is taxed on worldwide income. A non-resident is taxed only on income linked to a UAE permanent establishment, UAE-sourced income and income from a UAE nexus. Corporate Tax is 0% on taxable income up to AED 375,000 and 9% above that, subject to each regime's conditions.
Resident Versus Non-Resident Tax Scope
If a foreign company becomes UAE tax resident, it must account for its worldwide profits in the UAE. That matters most for holding and trading structures.
Registration and Filing Consequences
Resident persons must register with the Federal Tax Authority, then file an annual return with financial statements. Late registration carries an administrative penalty of AED 10,000. Say a founder finds they need to register after a bank review flags UAE-based management. Fixing it late is costly.
Permanent Establishment as a Separate Question
A permanent establishment is a different test. A foreign consultancy delivering client work from a Dubai office can be taxed through that fixed place of business without being resident. Keep the two analyses apart. For resident-specific rules, read the UAE Corporate Tax for residents guide.
Three Checks to Test Your Company's Place of Effective Management
Test your company's position with three checks. Look at where directors live and decide, where board meetings happen, whether records match reality, who holds bank signing authority and where senior staff work. If most answers point to the UAE, treat the company as likely UAE tax resident.
Check 1: Director Residence and Decision Location
- Map where each director lives and works.
- Note where decisions are taken in practice.
- Say a London director and a Dubai director split the board, but the Dubai director signs all major deals. The UAE leads.
Check 2: Board Meetings and Records
- Record where meetings take place, in person or online.
- Make sure minutes show real decisions.
- Minutes dated abroad while the chair joined from Dubai will not hold up.
Check 3: Bank Signing Authority and Senior Staff
- Review who controls accounts and payments.
- Identify where senior managers direct daily work.
- A finance lead approving payments from a Dubai workspace is a UAE factor. Document your conclusion before filing.
Qualifying Free Zone Person and Residency
A free zone company is a UAE tax resident because it is incorporated in the UAE, and residency alone does not remove 0% treatment. A Qualifying Free Zone Person pays 0% on qualifying income if it meets conditions such as adequate substance. Non-qualifying income is taxed at 9%.
Why Substance Sits Beside Residency
A company licensed in Meydan Free Zone is UAE incorporated, so it is resident. Qualifying status depends on separate statutory conditions. Holding board decisions and records in the UAE supports the substance case rather than undermining it.
Where Qualifying and Non-Qualifying Income Diverge
Cabinet and Ministerial decisions define qualifying categories, and excluded activities and de minimis rules apply. A company earning qualifying services income and excluded domestic income needs both streams reviewed. See qualifying vs non-qualifying income before assuming 0% applies.
Tax Residency Certificates and Treaty Relief
A tax residency certificate is issued by the Federal Tax Authority and can support a double tax treaty claim. A UAE resident company can apply if it meets the authority's conditions. The certificate does not set the Corporate Tax position itself.
When a Certificate Helps
A UAE company receiving dividends from a treaty country may need it to reduce withholding tax. Foreign counterparties and tax authorities often request one. The Federal Tax Authority issues it, not the free zone.
Dual Residency Risks
Another country may claim residency through its own management test. Treaty tie-breaker rules often look at place of effective management. A company with a UK-based and a Dubai-based director can face competing claims, so align records with the intended residence.
What This Means for a Meydan Free Zone Founder
A founder running a Meydan Free Zone company from the UAE should assume UAE tax residency and plan for registration, records and substance. Meydan Free Zone's mAccounting pillar offers bookkeeping, VAT registration support and Corporate Tax support, which helps keep the records these tests rely on.
Plan Residency Before You Apply
Decide where directors will live and take decisions before you set up. A founder moving from Europe who keeps an overseas company should check which entity holds contracts, because a UAE-managed foreign company may itself become UAE resident.
Keep Records That Match Reality
- mAccounting offers bookkeeping, VAT registration support and Corporate Tax support.
- Consistent books support residency and Qualifying Free Zone Person positions.
- Meydan Free Zone issues the Business License, Certificate of Formation, Share Register, and Memorandum and Articles of Association digitally.
Free Business Setup Cost Calculator
Calculate NowConclusion
UAE residence rules reward substance over paperwork. Where your directors decide, sign and keep records is what the Federal Tax Authority weighs. Map where decisions are made in your group and confirm your intended tax residence. A Meydan Free Zone company is UAE resident from incorporation, so the open question is whether any overseas entity in your group is also managed from here.
Ready to Launch Your Business in Dubai?
Let's ConnectReferences
- Federal Tax Authority (FTA), UAE, Corporate Tax guidance.
- Federal Decree-Law No. 47 of 2022 on the Taxation of Corporations and Businesses.