Table of Contents
Frequently Asked Questions
Does a landlord's insurance cover a tenant's stock and equipment in the UAE?
Usually not. A landlord's policy normally covers the building structure and common areas. A tenant's stock, fit-out, IT hardware and furniture need a separate commercial property policy, so check your lease and the landlord's cover before assuming you are protected.
Is property insurance mandatory for a business in the UAE?
Property All Risks cover is generally voluntary. However, landlords often require tenants to insure their fit-out and assets as a lease condition. Lenders financing equipment may also require cover and ask to be named as loss payee.
What is the difference between all risks and named perils cover?
A named perils policy pays only for events it lists, such as fire or lightning. An all risks policy covers any accidental loss unless the wording excludes it. This makes the exclusions list the most important part of an all risks policy.
Does Property All Risks insurance include loss of income?
No, not in the base property section. Business interruption cover is a separate extension. It pays gross profit and fixed costs such as rent and salaries during the indemnity period while premises are repaired.
How should a business calculate its sum insured?
Use the full replacement value of your assets, not their depreciated value. Build an asset register covering fit-out, equipment and stock with current replacement costs. Review the figure every year, because stock levels and equipment prices change.
Can a free zone company buy property insurance from an onshore insurer?
Yes. A Meydan Free Zone company can insure its own assets with an insurer licensed in the UAE. The Central Bank of the UAE regulates insurers and intermediaries. The policy schedule should name the actual premises the company occupies.
What happens if a business is underinsured at the time of a claim?
The insurer may apply a proportionate settlement. For example, if assets worth AED 800,000 are insured for AED 600,000, the insurer may pay only three-quarters of the loss. Insuring at full replacement value avoids this reduction.
Which events are commonly excluded from commercial property cover?
Common exclusions include wear and tear, gradual deterioration, inherent defects, war, nuclear risks and deliberate acts. Theft without forced entry, cash and electronic data are often limited. Terrorism may be available as an add-on.
Topic Summary
What Property All Risks Insurance Covers
Property All Risks insurance is a commercial policy that covers physical loss or damage to business assets from any cause not specifically excluded. It typically protects fit-out, machinery, stock and equipment against fire, water damage, theft and similar events. Cover depends on the wording, the sum insured and the exclusions.
Common Exclusions and Coverage Limits
Property All Risks policies exclude wear and tear, gradual deterioration, inherent defects, war, nuclear risks and deliberate acts. Many also limit theft without forced entry, cash and electronic data. Excess amounts and sub-limits apply per claim, so the schedule matters as much as the headline sum insured.
How the UAE Regulates Commercial Property Insurance
The Central Bank of the UAE regulates insurance companies and intermediaries. Buy cover only from licensed insurers or registered brokers. Free zone companies can insure assets with UAE-licensed insurers, and the policy applies to the premises named in the schedule.
Add-On Covers Worth Considering
Common add-ons include business interruption, public liability, machinery breakdown, goods in transit and terrorism cover. Business interruption matters most, because it replaces lost gross profit while premises are repaired, which the base property section does not do.
How to Arrange Property All Risks Cover
To arrange cover, list your assets, set a replacement-value sum insured, choose a registered broker, compare quotes on wording, add extensions and confirm the schedule before the policy starts. Review the sum insured every year.
Costs and Pricing Factors
Premiums are a rate applied to the sum insured. Insurers weigh business type, construction, fire protection, location, claims history and excess. No official standard rate exists, so a broker quote gives the actual figure.
Making a Claim and Avoiding Rejection
To claim, notify the insurer promptly, protect the damaged property, document the loss and submit proof of value. Claims are reduced or rejected for late notice, underinsurance, breached warranties or missing documents.
Property All Risks Insurance for UAE Businesses
Most founders in the UAE assume a landlord's building policy protects their stock, fit-out and equipment. It rarely does, and the gap usually shows only after a fire, flood or break-in. This guide explains what Property All Risks insurance covers, where it stops and how to set the right sum insured before you buy.
What Property All Risks Insurance Covers
Property All Risks insurance is a commercial policy that covers physical loss or damage to business assets from any cause not specifically excluded. It typically protects fit-out, machinery, stock and equipment against fire, water damage, theft and similar events. Cover depends on the wording, the sum insured and the exclusions.
Named perils policies pay only for listed events such as fire or lightning. An all risks policy covers any accidental loss unless the wording excludes it, so the exclusions list matters more than the cover list. The burden of proof also shifts: the insurer must show an exclusion applies.
Say a trading company's stock is damaged by a burst pipe. A narrow named perils policy may reject the claim. An all risks policy would normally respond.
Property All Risks vs Named Perils Cover
| Feature | Property All Risks | Named Perils |
|---|---|---|
| Scope of cover | Any accidental loss not excluded | Only events listed in the policy |
| Burden of proof on claim | Insurer must show an exclusion applies | You must show the loss matches a listed event |
| Typical exclusions | Wear and tear, war, nuclear risks, deliberate acts | Everything outside the named list |
| Flexibility for changing assets | New equipment is covered if the sum insured is updated | New assets are covered only for the named events |
| Suitability for stock and equipment | Better for varied stock, IT hardware and machinery | Suits low-value, low-risk asset bases |
Typical insured assets include:
- Fit-out and leasehold improvements
- Office equipment, IT hardware and furniture
- Stock, including goods in transit if extended
- Premises named in the schedule
A consultancy in a serviced office insures its laptops and furniture. The landlord insures the building.
Common Exclusions and Coverage Limits
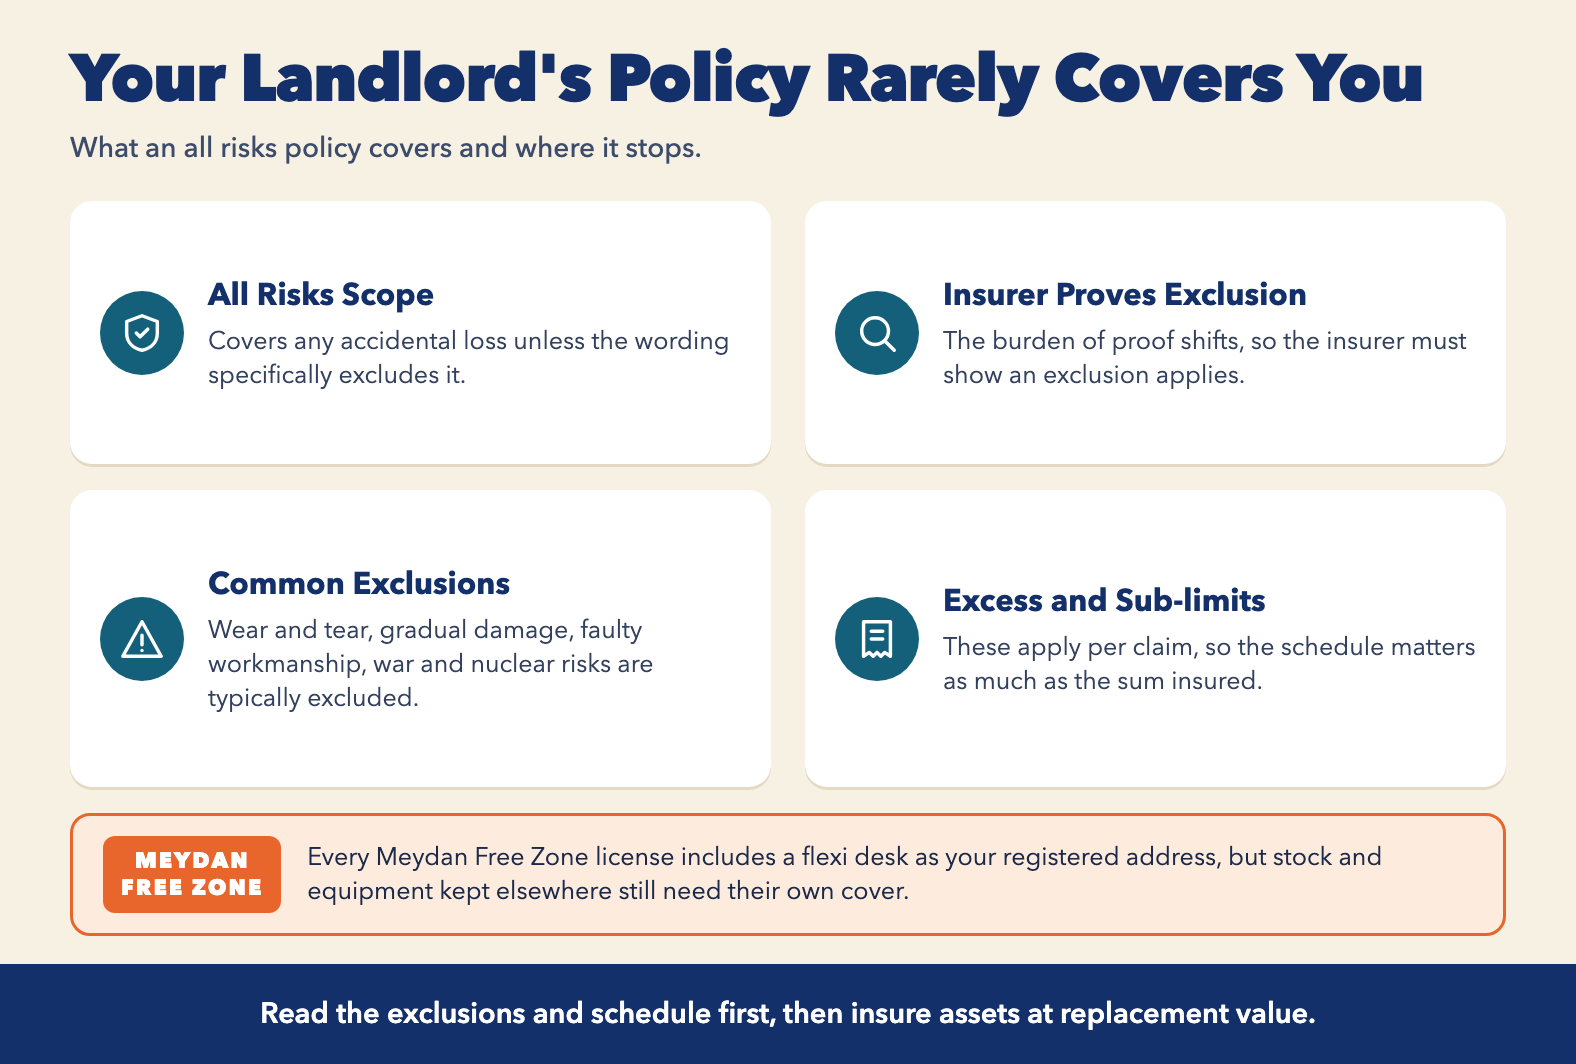
Property All Risks policies exclude wear and tear, gradual deterioration, inherent defects, war, nuclear risks and deliberate acts. Many also limit theft without forced entry, cash and electronic data. Excess amounts and sub-limits apply per claim, so the schedule matters as much as the headline sum insured.
- Wear, corrosion and gradual damage
- War and nuclear risks, with terrorism sometimes available as an add-on
- Faulty design or workmanship
- Consequential loss, unless business interruption is added
A restaurant's refrigeration fails from age. The spoiled stock claim is refused unless a specific extension applies.
The excess is the amount you bear per claim. Sub-limits cap items such as glass, cash or stock in the open. Warranties, such as fire alarm maintenance, can void a claim if breached. A warehouse policy may require working sprinklers, and a claim shrinks if maintenance records are missing.
How the UAE Regulates Commercial Property Insurance
The Central Bank of the UAE regulates insurance companies and intermediaries. Buy cover only from licensed insurers or registered brokers. Free zone companies can insure assets with UAE-licensed insurers, and the policy applies to the premises named in the schedule.
The cover is generally voluntary, but landlords and lenders often require it. Leases may require tenants to insure fit-out. A bank financing equipment may ask to be noted as loss payee. Review these terms before the policy is bound. For the separate third-party risk, read about general liability vs professional liability.
Add-On Covers Worth Considering
Common add-ons include business interruption, public liability, machinery breakdown, goods in transit and terrorism cover. Business interruption matters most, because it replaces lost gross profit while premises are repaired, which the base property section does not do.
If a fire closes a retail unit for months, rent and salaries continue while revenue stops. Business interruption covers the shortfall. Choose an indemnity period that reflects a realistic rebuild time, and base it on accurate profit projections.
- Public liability covers third-party injury or damage, a separate risk from your own assets
- Goods in transit suits traders moving stock between a warehouse and clients
How to Arrange Property All Risks Cover
To arrange cover, list your assets, set a replacement-value sum insured, choose a registered broker, compare quotes on wording, add extensions and confirm the schedule before the policy starts. Review the sum insured every year.
- Build an asset register. List fit-out, equipment and stock with locations, purchase dates and AED values.
- Set replacement value. Equipment bought for AED 200,000 that now costs AED 260,000 to replace should be insured at AED 260,000. Underinsurance can reduce a claim proportionately.
- Compare wording, not price alone. Two quotes may differ slightly in premium, but one may exclude water damage from internal pipes.
- Add extensions and confirm the schedule. Verify named premises and warranties. If you move offices mid-year, update the address by endorsement.
Costs and Pricing Factors
Premiums are a rate applied to the sum insured. Insurers weigh business type, construction, fire protection, location, claims history and excess. No official standard rate exists, so a broker quote gives the actual figure.
- Offices price lower than warehouses or commercial kitchens
- Fire protection and maintenance records lower risk
- A higher excess lowers premium but raises retained risk
Raise the excess before cutting the sum insured. Treat insurance as a recurring cost and review it every year. Check VAT treatment of premiums with the Federal Tax Authority.
Making a Claim and Avoiding Rejection
To claim, notify the insurer promptly, protect the damaged property, document the loss and submit proof of value. Claims are reduced or rejected for late notice, underinsurance, breached warranties or missing documents.
- Loss notification and incident report
- Police report for theft or fire
- Invoices, asset register and repair estimates
A loss adjuster may assess the damage. If you insure AED 600,000 of assets actually worth AED 800,000, the insurer pays only a proportion of the loss. Learn how assessing insurance claims works to understand the other side of the process.
What This Means for a Meydan Free Zone Company
A Meydan Free Zone company insures its own assets, stock and equipment, and the policy should name the premises it occupies. Meydan Free Zone issues the Business License digitally but does not sell property insurance. Arrange cover separately after confirming asset values and lease terms.
Flexi-desk, office and warehouse set-ups need different cover. Insure what you own, not the landlord's building. A single-shareholder company set up through Fawri that keeps equipment at home should confirm the policy covers that location.
Budget the premium as a recurring cost next to license and workspace costs. Use the Cost Calculator for license and setup costs, then add insurance separately. For liability risks, see accidents and liabilities insurance.
Free Business Setup Cost Calculator
Calculate NowConclusion
A Property All Risks policy works only if the sum insured, exclusions and extensions match how your business operates. Accurate valuations, clear wording and good records decide claims. List your assets, set replacement values and request broker quotes so insurance is budgeted from day one. Every Meydan Free Zone license includes a flexi desk as your registered address, but stock and equipment kept elsewhere still need their own cover.
Ready to Launch Your Business in Dubai?
Let's Connect