Table of Contents
Frequently Asked Questions
Which documents does a bank usually need to finance an import shipment in the UAE?
Banks typically ask for the commercial invoice, packing list, bill of lading or airway bill, certificate of origin, insurance certificate and the underlying sales contract. They also review the company's business license and KYC file. Every document must agree on parties, values, quantities and dates.
Why do banks reject trade finance documents that look correct?
Banks compare documents against each other, not just individually. A different consignee name, a quantity variance or a shipping date after a letter of credit expiry can trigger a refusal. A license activity that does not cover the goods traded can also stop the application.
Do foreign trade documents need attestation before a UAE bank accepts them?
Many foreign documents, such as an overseas supplier's contract or corporate papers, need attestation before a UAE bank will rely on them. Requirements vary by bank and document type. Attesting early avoids a query that pauses the financing review.
Who supervises banks that handle trade finance in the UAE?
The Central Bank of the UAE supervises banks and sets the AML and compliance framework behind trade finance checks. Customs authorities handle customs declarations. The Federal Tax Authority (FTA) handles VAT, and the relevant free zone authority handles licensing.
Can a free zone company obtain trade finance from a UAE bank?
A free zone company can apply for trade finance, but approval rests with the bank's credit and compliance review. The bank reads the business license activity against the goods being traded. A Meydan Free Zone company receives its Business License, Certificate of Formation, Share Register and Memorandum and Articles of Association digitally, which gives the bank its core corporate papers.
How do banks detect duplicate financing on the same invoice?
Banks check invoice numbers, bill of lading references and shipment details against their own records and, where needed, confirm with carriers, insurers or counterparties. Member banks can also submit invoices to UAE Trade Connect, which flags possible duplicates across participating banks. A flag prompts a closer review rather than proving fraud.
Does a digital signature on a trade document hold up in the UAE?
Electronic signatures can be valid under UAE law when they meet the legal requirements, though some document types are excluded. A bank may still ask for the original or a specific signature format under its own policy. Confirm acceptance with the bank before relying on a digitally signed trade document.
What should a new trading company prepare before approaching a bank for trade finance?
Prepare a consistent set of invoices, shipping papers and contracts that match the company name and license activity exactly. Have the corporate documents, ownership details and any required attestations ready for the KYC review. A new company with no trading history should expect closer scrutiny and should not assume a large facility will be approved.
Topic Summary
What UAE Trade Connect Means for Traders
UAE Trade Connect is a blockchain-based platform that member UAE banks use to check invoices for fraud and duplicate financing. It went live commercially on 19 April 2021, co-created by Etisalat Digital (now e&) and seven UAE banks, including Emirates NBD and Mashreq. It has since been rebranded as Haifin.
Documents Banks Check Before Financing a Trade
Banks typically review the commercial invoice, packing list, bill of lading or airway bill, certificate of origin, insurance certificate and the underlying sales contract. They compare quantities, values, parties, dates and descriptions across every document. Any discrepancy can delay financing or trigger a refusal. A duplicate-financing check adds a layer on the invoice, but the bank's own cross-check of these papers still decides the outcome.
How Banks Verify Trade Finance Documents
Banks verify trade finance documents in sequence. They confirm the client's identity and license, check each document for completeness and cross-match the details. They then validate authenticity with issuers and screen all parties for sanctions and anti-money laundering (AML) risk before approving or querying the transaction. UAE Trade Connect supports the authenticity step for member banks by flagging invoices that may already be financed elsewhere.
Who Oversees Trade Finance Verification in the UAE
The Central Bank of the UAE supervises banks and sets the AML and compliance framework behind trade finance checks. Customs authorities handle customs declarations, and the Federal Tax Authority (FTA) handles VAT. A free zone authority handles licensing for its companies. UAE Trade Connect itself is a commercial platform, not a regulator.
Common Reasons Verification Fails
Verification usually fails because of mismatched details, license activity that does not cover the goods, missing attestation, unclear counterparties or incomplete KYC. Most are paperwork errors you can fix before submission, so checking your documents against each other first saves time.
What This Means for a Meydan Free Zone Trader
A Meydan Free Zone company receives its Business License, Certificate of Formation, Share Register and Memorandum and Articles of Association (MoA/AoA) digitally. That gives banks the core corporate papers. mCore supports business bank account setup, though it does not guarantee approval or trade finance.
Conclusion
Platforms such as UAE Trade Connect help catch duplicate financing, but most delays come down to document discipline. Banks finance paperwork that agrees with itself and with the license behind it. Before applying for a facility, audit your invoices, shipping papers and license activity against each other, and fix every discrepancy first. A Meydan Free Zone company receives its Business License digitally, so the licensed name and activity are easy to check against every invoice.
UAE Trade Connect: How Banks Verify Trade Finance Documents
Banks in the UAE finance trade on the strength of the paperwork, not the deal, so one mismatched invoice can hold up a shipment. Many banks also run invoices through UAE Trade Connect, a shared platform built to catch duplicate financing. This guide explains what that platform does, how banks verify trade finance documents and which errors cause delays.
What UAE Trade Connect Means for Traders
UAE Trade Connect is a blockchain-based platform that member UAE banks use to check invoices for fraud and duplicate financing. It went live commercially on 19 April 2021, co-created by Etisalat Digital (now e&) and seven UAE banks, including Emirates NBD and Mashreq. It has since been rebranded as Haifin.
Definition and Scope
The platform checks invoice data, not your whole file. Banks submit invoice details, and the system flags possible duplicates, such as an invoice already financed through another member bank. It does not approve financing, and a flagged match is not proof of fraud. Each bank still runs its own document checks.
Say a Dubai trader finances a shipment of electronics. The bank reviews the paperwork, not the product quality. That protects the bank, and it protects you, because funds are only released against evidence that the shipment exists.
Trade Documents and What Banks Verify
| Document | Role in the File | What the Bank Checks |
|---|---|---|
| Commercial invoice | Records the sale and its price | Values, parties and goods description |
| Packing list | Itemises what is physically shipped | Quantities and weights against the invoice |
| Bill of lading or airway bill | Proves the goods were shipped | Shipment date and consignee |
| Certificate of origin | States where the goods were made | Country of origin and issuer |
| Insurance certificate | Covers loss or damage in transit | Coverage and beneficiary |
Why Verification Matters Commercially
Unverified documents delay payment and credit release. Banks guard against document fraud and duplicate financing. Say a trader presents the same invoice to two lenders. Verification is what exposes it.
Clean paperwork also shortens the review. The World Bank has published research on the global trade finance gap that smaller businesses face.
Documents Banks Check Before Financing a Trade

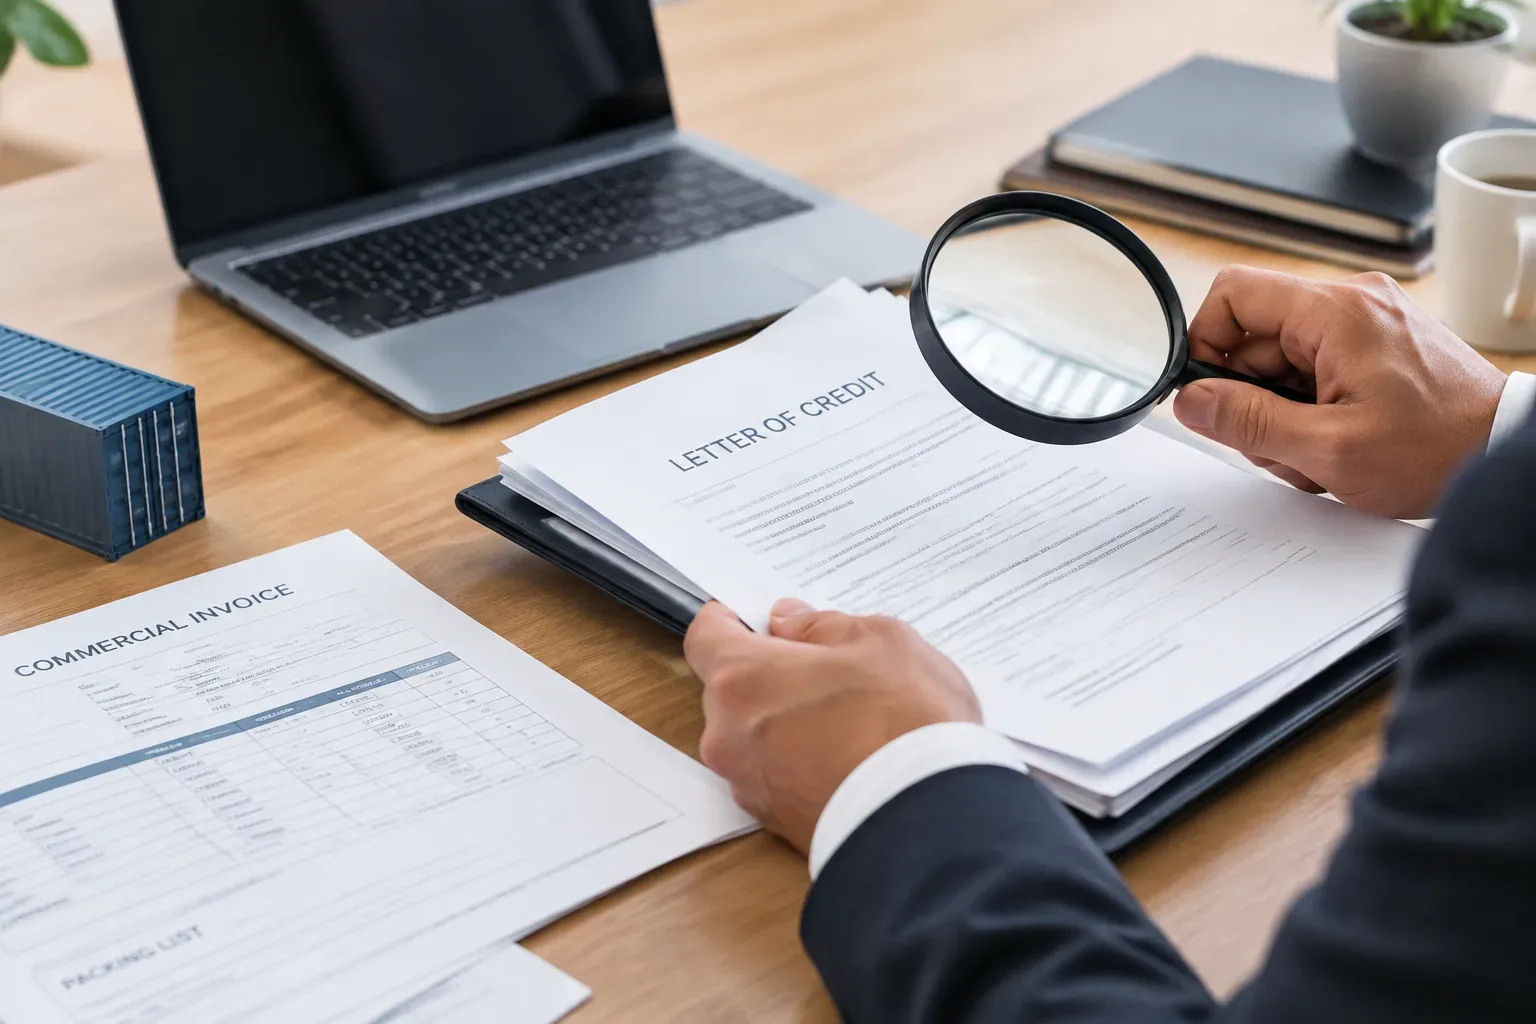
Banks typically review the commercial invoice, packing list, bill of lading or airway bill, certificate of origin, insurance certificate and the underlying sales contract. They compare quantities, values, parties, dates and descriptions across every document. Any discrepancy can delay financing or trigger a refusal. A duplicate-financing check adds a layer on the invoice, but the bank's own cross-check of these papers still decides the outcome.
Core Commercial Documents
- The invoice, packing list and contract must agree on values and quantities.
- Party names must match the trade license exactly.
- Goods descriptions must be consistent on every page.
An invoice that uses a trading name different from the licensed name is a common failure. The bank cannot confirm it is the same entity.
Transport and Origin Papers
The bill of lading or airway bill confirms the shipment and its dates. The certificate of origin supports customs treatment. Port and carrier details must tally with the invoice. A bill of lading dated after a letter of credit expiry will usually be refused. Port operators such as DP World are among the parties whose shipping records feed this chain.
Attested and Notarised Papers
Foreign documents often need attestation before a UAE bank accepts them. An overseas supplier's contract without attestation is a typical stumbling block. Notarisation adds a further layer of proof for some papers. A trusted representative can handle the process on your behalf. See how to attest documents in Dubai and the essential documents for an import-export business in Dubai.
How Banks Verify Trade Finance Documents
Banks verify trade finance documents in sequence. They confirm the client's identity and license, check each document for completeness and cross-match the details. They then validate authenticity with issuers and screen all parties for sanctions and anti-money laundering (AML) risk before approving or querying the transaction. UAE Trade Connect supports the authenticity step for member banks by flagging invoices that may already be financed elsewhere.
Step 1: Confirm the Client and License
- The bank runs Know Your Customer (KYC) checks on the company, owners and activity.
- License activity must match the goods traded.
- A license listing general trading may still fall short for restricted goods.
Step 2: Cross-Match Document Details
- Values, quantities, dates, parties and ports are compared.
- The bank raises discrepancies, which the applicant may choose to waive.
- Even a small quantity variance can be flagged, depending on the letter of credit terms.
Step 3: Validate Authenticity
- The bank contacts issuers, carriers or insurers.
- It checks for duplicate financing, which member banks can also screen through UAE Trade Connect.
- A carrier may confirm a bill of lading number directly.
Step 4: Screen and Decide
- All parties and routes face sanctions and AML screening.
- A shipment routed through a high-risk jurisdiction draws extra queries.
- The bank approves, queries or declines, with reasons.
The Central Bank of the UAE supervises banks and sets the anti-money laundering rules behind these checks.
Who Oversees Trade Finance Verification in the UAE
The Central Bank of the UAE supervises banks and sets the AML and compliance framework behind trade finance checks. Customs authorities handle customs declarations, and the Federal Tax Authority (FTA) handles VAT. A free zone authority handles licensing for its companies. UAE Trade Connect itself is a commercial platform, not a regulator.
Federal and Emirate-Level Roles
A VAT-compliant invoice can still fail because of a customs mismatch. The Federal Tax Authority reviews VAT, not customs matters.
Free Zone Licensing Role
The free zone authority issues the business license. Banks then read the license activity against the trade. A trader whose activity wording does not cover the goods can find a facility blocked.
Common Reasons Verification Fails
Verification usually fails because of mismatched details, license activity that does not cover the goods, missing attestation, unclear counterparties or incomplete KYC. Most are paperwork errors you can fix before submission, so checking your documents against each other first saves time.
Mismatches and Missing Papers
- The invoice names a different consignee than the shipping document.
- The certificate of origin or insurance certificate is missing.
- Dates fall outside the financing terms.
Profile and Compliance Gaps
A weak KYC file or unexplained ownership slows everything. A new company with no trading history requesting a large facility will face closer questions. The same gaps often drive account refusals, covered in business bank account rejection in the UAE.
What This Means for a Meydan Free Zone Trader
A Meydan Free Zone company receives its Business License, Certificate of Formation, Share Register and Memorandum and Articles of Association (MoA/AoA) digitally. That gives banks the core corporate papers. mCore supports business bank account setup, though it does not guarantee approval or trade finance.
Corporate Papers Banks Request
Align your license activity with the goods you trade. Present the license beside your first invoice so names and activities match.
Support Services Relevant to Trade Documents
- mCore supports business bank account setup.
- mAssist, part of Meydan Plus, includes document translation, useful before a bank reviews a supplier contract.
- mAccounting offers VAT registration support and bookkeeping, which keep invoice records in order.
- None of these guarantees a facility.
Free Business Setup Cost Calculator
Calculate NowConclusion
Platforms such as UAE Trade Connect help catch duplicate financing, but most delays come down to document discipline. Banks finance paperwork that agrees with itself and with the license behind it. Before applying for a facility, audit your invoices, shipping papers and license activity against each other, and fix every discrepancy first. A Meydan Free Zone company receives its Business License digitally, so the licensed name and activity are easy to check against every invoice.
Ready to Launch Your Business in Dubai?
Let's Connect